Pay by Phone Casinos Australia 2026: A Cynic’s Guide to Mobile Deposits
Forget the romance of the digital wallet. For a specific, stubborn segment of Australian gamblers, the only currency that matters is the one already sitting in their carrier account. Pay by phone casinos in Australia for 2026 aren’t a futuristic fantasy; they’re a pragmatic, if slightly clunky, reality. This guide cuts through the marketing fog to explain exactly how this payment method works, who it’s for, and why you should probably keep your deposit limits low.
The core appeal is brutally simple: you don’t need a bank account, a credit card, or even a dedicated e-wallet. Your mobile number is your financial identity. A deposit is charged to your monthly phone bill or deducted from your prepaid credit. It’s the financial equivalent of putting a round on a tab and settling up later. The trade-off is immediate and severe: while getting money in is as easy as sending a text, getting money out requires a completely different strategy. This isn’t a two-way street; it’s a one-way deposit lane with a mandatory U-turn at the exit.
The Mechanics: How a Carrier Becomes Your Unlikely Banker
The technology behind pay by phone deposits is a relay race between three parties: you, the casino’s payment processor, and your mobile network operator (MNO). When you select this deposit method, you enter your phone number. The processor sends a unique, encrypted code to your MNO. Your MNO then either adds the amount to your next bill or, for prepaid users, immediately deducts it from your available balance. A confirmation SMS is sent back, and the funds appear in your casino account, often within seconds. The entire transaction is authenticated by your SIM card, making it surprisingly secure against certain types of fraud.
But security comes with a paper trail. Every transaction is logged by your carrier. This isn’t a concern for privacy purists, but for the average player, it simply means your gambling expenditure is itemized on your phone bill or prepaid statement. There’s no anonymity here. The MNO acts as a silent, billing-obsessed partner in your entertainment, and they take their role very seriously. The processing fees, which the casino typically absorbs, are higher than those for e-wallets or bank transfers, which is a key reason this method isn’t universally offered.
The system’s architecture reveals its primary limitation. The carrier is extending you a micro-loan for postpaid users or facilitating a direct spend for prepaid users. They are not a bank, and they have no appetite for the risk associated with facilitating withdrawals. Their entire infrastructure is built for one-directional billing. Asking them to send money back to you would be like asking your electricity provider to refund you for a lightbulb you didn’t burn out last month—it’s just not how their systems are designed to operate.
Why It Still Exists in 2026: The Unsexy Truth
Given the proliferation of instant bank transfers, PayPal, and a dozen crypto options, the persistence of pay by phone casinos seems odd. The answer lies in demographics and friction. For a player who is unbanked, underbanked, or simply distrustful of linking primary financial accounts to gambling sites, this method offers a psychological barrier. The loss is capped at what’s on the phone. It’s a form of enforced bankroll management, albeit a crude one. You can’t chase losses with money you don’t have loaded.
There’s also the sheer, dumb convenience for casual play. Depositing $20 to play pokies for an hour doesn’t require logging into a bank portal or opening a separate app. It’s a three-tap process embedded in the casino’s cashier. This low-friction experience is a powerful hook for impulsive, low-stakes sessions. The industry knows this. The method is deliberately kept simple to capture deposits that might not happen if more steps were required. It’s not about providing a superior service; it’s about removing obstacles to spending.
The Australian regulatory landscape, managed by the Australian Communications and Media Authority (ACMA), also plays a role. While ACMA actively blocks illegal offshore gambling sites, the payment method itself operates in a gray zone. It’s a legitimate carrier service being used for a purpose that regulators are still catching up to. This regulatory lag has allowed the method to persist, serving as a convenient on-ramp for players at sites that may or may not be fully compliant with Australian interactive gambling laws.
PayID Casino No Deposit Bonus Australia 2026: The Math Behind the “Free” Money
The Withdrawal Problem: Your Money’s One-Way Ticket
Here is the central, non-negotiable fact of pay by phone casinos: you cannot withdraw using this method. Period. Any winnings derived from a phone deposit must be cashed out via an alternative channel. This creates a mandatory, often inconvenient, step in the cash-out process. You will need to have, or be willing to set up, an account with a bank, an e-wallet like Skrill or Neteller, or have a cryptocurrency wallet ready. The casino will typically require you to withdraw to the same method you used for your last deposit, if possible, which forces the setup of a new payment method for the withdrawal.
This isn’t a minor inconvenience; it’s a fundamental design flaw from the player’s perspective. It means your “simple” deposit method is only half of a complete transaction. The process of verifying a new withdrawal method can take 24-48 hours, during which your winnings sit in a state of limbo. For the player who deposited via phone for its simplicity, this subsequent requirement for documentation and verification is a jarring and frustrating pivot. It transforms a seamless deposit into a two-stage, identity-heavy cash-out process.
The reason for this one-way system is purely commercial. The margins on processing pay by phone deposits are thin for the casinos, and the chargeback risk is non-existent because the carrier guarantees the payment. Offering withdrawals would invert this model, introducing settlement delays, verification costs, and financial risk that the casinos have no incentive to shoulder. The method exists to capture deposits, not to facilitate a fluid banking relationship. It’s a funnel, not a vault.
Comparing the Landscape: What You Actually Get
Not all pay by phone services are created equal. The experience varies significantly based on your carrier and the specific payment gateway the casino uses. The two primary systems are Boku and Payforit, which operate across multiple carriers, and direct carrier billing agreements that some larger operators have with specific networks. The limits, fees, and processing times can differ, though the fundamental one-way rule remains constant. Here’s a typical breakdown of what you’ll encounter at casinos offering this method.
| Feature | Typical Range / Condition | The Fine Print |
|---|---|---|
| Minimum Deposit | A$10 – A$30 | Often higher than other methods to justify processing costs. Some casinos set a A$20 floor for phone deposits. |
| Maximum Deposit | A$30 – A$100 per transaction | A hard cap imposed by carriers. Daily and monthly limits are lower than for any other banking method. |
| Processing Fee | 0% – 15% | Casinos may absorb the fee or pass it on. A 15% fee on a A$20 deposit is a A$3 cost before you even place a bet. |
| Deposit Speed | Instant to 5 minutes | Usually the fastest part of the entire process. Funds are available for play almost immediately. |
| Withdrawal Availability | None | Impossible. You must use an alternative method for all cash-outs. |
| Availability by Carrier | Major carriers only | Telstra, Optus, Vodafone are typically supported. Smaller MVNOs are often excluded. |
The fee structure is where the real cost of convenience becomes apparent. A 10% fee on a A$50 deposit is a A$5 premium. Over a year of weekly deposits, that’s A$260 in pure transaction costs. Compare that to a bank transfer or an e-wallet, where fees are often negligible or zero for standard transactions. The pay by phone method is, in essence, a convenience tax. It’s the price you pay for not having to type in a 16-digit card number.
The low transaction limits are another deliberate design feature. Carriers set these caps to minimize their own risk exposure. For the casual player depositing A$20 for a quick session, it’s fine. For anyone attempting to manage a serious bankroll, the method is practically useless. You cannot make the large, strategic deposits that some bonus offers require. The system is built for micro-transactions, not for professional play. It’s a slot machine’s best friend, not a blackjack strategist’s.
The Legal and Regulatory Maze in Australia
Australia’s Interactive Gambling Act 2001 (IGA) and its subsequent amendments create a complex environment for all online gambling, and pay by phone casinos are no exception. The IGA primarily targets the provision of illegal interactive gambling services to Australian residents. It does not explicitly criminalize the act of a player placing a bet on an offshore site. This legal nuance is the gray area in which these casinos operate. They are offshore entities, often licensed in jurisdictions like Curaçao or Malta, accepting Australian players.
The role of the ACMA is to enforce the IGA by blocking access to illegal gambling sites and, crucially, by pressuring payment providers to block transactions to these sites. In recent years, ACMA has successfully compelled major Australian banks and some payment processors to implement blocks. However, the direct carrier billing channel has proven more difficult to regulate. The transaction appears as a standard charge to a telecom service, making it less transparent to financial regulators than a direct bank transfer to a known gambling operator. This opacity is a feature, not a bug, for the operators.
For the player, the legal risk is minimal but not zero. The IGA does not contain provisions for prosecuting individual bettors. The practical risk is not legal action, but the lack of recourse. If an offshore casino operating via pay by phone deposits decides to withhold your winnings or close your account, you have no meaningful path to complaint within the Australian legal system. Your regulator is focused on the provider, not the player. You are operating without a safety net, relying solely on the casino’s goodwill—a notoriously thin commodity in this industry.
Beyond the Deposit: Game Selection and Software
The method of deposit has no bearing on the games available to you once the funds are in. A pay by phone deposit grants you access to the same game library as any other payment method at that casino. The quality and variety of games are determined by the casino’s software partnerships, not its payment processors. You’ll find the same suite of pokies from providers like Aristocrat, IGT, and Pragmatic Play, the same table games from Evolution Gaming, and the same progressive jackpots. The deposit method is a front-end ticket; the game lobby is the same concert hall.
However, there is an indirect correlation. Casinos that heavily promote pay by phone deposits often cater to a more casual, mobile-first audience. Their game lobbies may be optimized for shorter sessions and feature more low-volatility pokies and instant-win games. They might prioritize a streamlined mobile interface over a vast, complex desktop client. The user experience is tailored to the player who deposits $20, plays for 30 minutes on the bus, and logs off. It’s a different ecosystem than the one built for the high-roller at a dedicated VIP lounge.
The software also handles the payment interface. A well-integrated pay by phone option will feel seamless within the casino’s cashier. A poorly integrated one will redirect you to a clunky third-party page, ask for repeated verification, and create a disjointed experience. The quality of this integration is a good litmus test for the casino’s overall technical investment. If they can’t be bothered to make the deposit process smooth, the rest of the platform is likely held together with digital duct tape.
New Casinos and the Pay by Phone Gambit
New online casinos entering the Australian market in 2026 are acutely aware of the payment landscape. Offering pay by phone is a strategic move to capture a segment of the market that is underserved by traditional banking methods. For a new operator, it’s a way to differentiate and attract players who are wary of sharing financial details or who face rejection from banks due to gambling blocks. It’s a low-hanging fruit in the payment method lineup, a checkbox that signals “we cater to everyone.”
But new casinos also come with the highest risk. The pay by phone method, with its lack of withdrawal capability and reliance on carrier trust, can be a perfect tool for a disreputable operator. They can happily accept your deposits, but when it comes time to pay out, the process of setting up an alternative withdrawal method gives them ample opportunity to stall, request excessive documentation, or simply find a pretext to void your winnings. The method’s inherent friction at the withdrawal stage is a gift to any casino looking to delay payouts.
Due diligence is therefore non-negotiable. Before depositing a single dollar via your phone, you must investigate the casino’s license, its ownership group, and its reputation among player communities. Look for a license from a reputable jurisdiction like Malta (MGA) or the UK (UKGC), not just a Curaçao e-gaming license, which offers minimal player protection. Read independent reviews, but discount the overly positive ones that read like press releases. The real information is in the complaints forums, where you’ll find the unvarnished truth about payout delays and customer service runarounds.
The Psychology of the “Free” Deposit
Casinos love to frame pay by phone as a “free” and “instant” deposit method. The word “free” is doing a lot of heavy lifting here. While the casino may not charge you a fee, the carrier might. And even if the transaction itself is fee-free, you’re still paying with something more valuable than money: convenience that enables impulsive spending. The ease of the deposit is the trap. It’s designed to lower the psychological barrier to parting with your cash. It’s the casino equivalent of a one-click buy button, and it’s engineered to exploit your momentary desire to play.
The “instant” part is also a double-edged sword. The speed means there’s no cooling-off period. You don’t have time to reconsider whether you really want to deposit that $50. The money is there, and the pokies are spinning before your rational brain can object. This immediacy is a core feature of modern gambling design, and pay by phone is its most efficient delivery mechanism. It’s not a service for the disciplined player; it’s a service for the player who lives in the moment, for better or worse.
And let’s be clear: casinos are not charities. They don’t offer convenient deposit methods out of the goodness of their hearts. They offer them because they work. They increase deposit frequency and volume from a specific player demographic. The “VIP treatment” you might receive at such a casino is like a free drink at a pokie machine—just enough to keep you seated, playing, and spending. The house always has the math on its side, and the frictionless deposit method is just another tool to ensure the game continues.
Responsible Gambling: The One-Way Street Has Guardrails
The very structure of pay by phone deposits offers a crude form of responsible gambling control. The low transaction limits act as a natural brake on excessive spending. You cannot deposit A$1,000 in a single transaction via this method. For some players, this enforced limitation is the primary reason they use it. It’s a self-imposed constraint that doesn’t require willpower, just a carrier’s policy. It’s the financial equivalent of leaving your credit card at home when you go to the pub.
However, this guardrail is easily circumvented. The limit is per transaction, not per day. A determined player can make multiple deposits across different casinos, or even multiple deposits at the same casino over a short period, until their carrier balance is depleted or their bill reaches an uncomfortable level. The system doesn’t aggregate spending across platforms. It’s a series of isolated transactions, not a holistic view of your gambling expenditure. True responsible gambling requires a tool that sees the whole picture, not just one pixel of it.
Australian regulations mandate that licensed operators provide tools like deposit limits, session time limits, and self-exclusion options. The problem is that most pay by phone casinos are offshore and not subject to these Australian mandates. Their responsible gambling tools, if they exist at all, are voluntary and often buried deep in the settings menu. The player is left to rely on their own discipline and the carrier’s transaction limits—a combination that is far from foolproof. The responsibility falls squarely on the individual, in an environment designed to erode it.
What are the actual fees for using pay by phone at Australian casinos?
Fees vary by casino and carrier, but typically range from 0% to 15% of the deposit amount. Some casinos absorb the fee entirely, while others pass it on to the player. A A$20 deposit could incur a fee of up to A$3. Always check the casino’s banking page and your carrier’s terms for prepaid transactions to understand the total cost before committing.
Can I claim a welcome bonus if I deposit with my phone?
Yes, in most cases you can. However, some casinos may exclude pay by phone deposits from bonus eligibility or apply different wagering requirements. This is because the method carries higher processing costs for the operator. Always read the bonus terms and conditions carefully before depositing to ensure your chosen payment method qualifies.
How long does a deposit take to appear in my account?
Deposits are typically instant or take no more than 5 minutes. The funds are transferred directly via your mobile carrier’s billing system. If a deposit doesn’tappears immediately, contact the casino’s support team. The delay is almost always on the casino’s side, not the carrier’s, as they perform internal fraud checks before crediting your account.
What happens if I try to withdraw to my phone balance?
It’s not possible. The payment system is designed for one-way transactions only. Any winnings must be withdrawn to a bank account, e-wallet, or other supported method. The casino will require you to set up and often verify an alternative payment method before processing any cash-out request.
Is my financial information safe with this method?
Yes, in the sense that you are not sharing bank or card details with the casino. Your transaction is authenticated by your SIM and processed by your carrier. The risk shifts from financial data theft to carrier account security. Ensure your phone is PIN-protected and monitor your phone bill or prepaid balance for unauthorized charges.
Are pay by phone casinos legal in Australia?
The legality is complex. The Interactive Gambling Act targets the provision of illegal gambling services by operators, not the players themselves. Most pay by phone casinos are offshore and operate in a legal gray area. While players are not typically prosecuted, they have no legal recourse if disputes arise with an unlicensed operator.
The Verdict: A Tool for a Specific Job
Pay by phone casinos in Australia are not a comprehensive banking solution. They are a niche tool for a specific purpose: making small, impulsive deposits with maximum convenience and minimal financial disclosure. The method’s strengths—speed, simplicity, and a built-in spending cap—are also its weaknesses. The low limits, high potential fees, and absolute inability to withdraw make it impractical for anything beyond casual, low-stakes play. It’s the financial equivalent of a takeaway coffee: quick, satisfying in the moment, but not something you’d build a meal plan around.
The regulatory environment adds another layer of caution. Depositing at an offshore casino via your phone bill means you are operating outside the protective framework of Australian consumer law. Your recourse in case of a dispute is limited to the casino’s internal complaints process, which is about as reliable as a chocolate teapot. The convenience of the deposit method should not blind you to the fundamental risks of playing at an unregulated site. The house always wins, but at an illegal casino, they might also take your deposit and vanish.
For the player who understands these trade-offs and uses the method accordingly—small deposits, strict limits, no expectation of quick withdrawals—it can be a perfectly functional option. For anyone else, the drawbacks likely outweigh the benefits. The industry offers this method not because it’s the best for the player, but because it’s effective at capturing deposits that might otherwise be lost to hesitation. It’s a tool of convenience, and like all tools, its value depends entirely on the job you’re using it for. Just don’t expect the casino to thank you for your loyalty with anything more than a automated email and a 50% reload bonus with 60x wagering. The real “free gift” is the lesson in how the industry really works.
That’s the real “free gift” — the lesson in how the industry really works.
The real friction point isn’t the deposit. It’s the inevitable moment you win something and realize you need to set up a Skrill account you never wanted. That’s when the “convenience” reveals itself as a one-way valve. The carrier got their money instantly. The casino got your action. You got a pending withdrawal request and a request to upload a photo of your driver’s license. The system is optimized for one direction, and it’s not the direction where money flows back to you.
Dragon Link Online Pokies Australia 2026: The Math Behind the Neon Glow
Consider the actual user experience at 2 AM on a Sunday. You deposit A$30 via your Optus prepaid balance to chase a bonus on some new pokie. You win A$150. Great. Now what? You navigate to the withdrawal page, select bank transfer, enter your BSB and account number, and wait. The casino’s finance team doesn’t work weekends. Your request sits in a queue until Monday morning. Then it takes 24-48 hours to process. Then another 1-3 business days for the bank transfer to clear. By the time you see that A$150, it’s Thursday, and you’ve already forgotten what you were going to spend it on. The deposit took 3 seconds. The withdrawal takes a week. That’s the asymmetry you’re signing up for.
The Prepaid vs. Postpaid Divide
There’s a critical difference in how this payment method affects you depending on whether you’re on a prepaid or postpaid plan, and most guides gloss over it entirely. For postpaid users, the deposit is essentially a short-term loan from your carrier. The charge appears on your next bill, giving you a brief window before the money actually leaves your bank account. This creates a peculiar psychological effect: the gambling happens now, but the financial consequence is deferred. It’s the same temporal disconnect that makes credit cards dangerous for impulsive spenders, just on a smaller scale.
Prepaid users face a different reality. The money is deducted immediately from your available credit. There’s no deferral, no grace period. If you have A$50 in credit and deposit A$30 to a casino, you’re left with A$20 for calls, texts, and data until you top up again. This creates a hard, tangible limit that postpaid users don’t experience. The prepaid model is actually more honest about the transaction: you’re swapping phone credit for casino credit, and both are finite resources that deplete in real time. There’s a certain brutal clarity to it that the postpaid system lacks.
The carrier’s perspective differs too. For postpaid users, they’re extending a micro-credit facility with built-in fraud detection. For prepaid users, they’re simply facilitating a balance transfer. The risk profile is different, which is why some carriers impose stricter limits on prepaid transactions. If you’re trying to figure out why your A$20 deposit was rejected when your mate’s identical deposit went through, the answer might be sitting in the fine print of your respective plans. The system treats you differently based on how you pay your phone bill, which is a level of nuance that most casino marketing materials conveniently ignore.
Why do some casinos reject pay by phone deposits under A$10?
The processing cost for the casino is fixed regardless of transaction size. A A$5 deposit might cost the casino A$0.50 in carrier fees, which represents a 10% margin hit. For very small transactions, the economics don’t work. Most casinos set a minimum of A$10 or A$20 to ensure the deposit covers their processing costs and still leaves room for the house edge to do its work. It’s not about protecting you from small bets; it’s about protecting their margins.
Can I use pay by phone to deposit at multiple casinos in one day?
Technically yes, but practically you’ll hit carrier-imposed limits quickly. Most carriers cap daily transactions at A$100-A$200 across all merchants. Once you hit that ceiling, you’re done until the next billing cycle. Some casinos also implement their own daily deposit limits for this method, typically around A$300. The system is designed for occasional, small deposits, not for funding a serious gambling session across multiple platforms.
The carrier’s fraud detection algorithms also watch for unusual patterns. Multiple deposits to different gambling merchants within a short timeframe can trigger a temporary block. This is ostensibly for your protection, but it’s really about the carrier managing their risk exposure. If you suddenly start making five A$20 deposits to five different casinos in an hour, the system flags it as potential account compromise. Your gambling habit gets treated like a security breach, which tells you everything you need to know about how the industry really views this payment method.
Best Aussie Pokies Online Australia 2026: A Cynic’s Guide to Not Losing Your Shirt
And that’s the thing nobody tells you when you’re setting up that first deposit. The convenience is real, but it comes with invisible tripwires. The carrier is watching, the casino is calculating, and you’re somewhere in the middle, thinking you’ve found a clever workaround. The only thing you’ve actually found is a different set of constraints. The money still flows one way, the house still has the edge, and your phone bill still arrives at the end of the month with a line item that reads like a confession.
The Verification Dance: KYC Meets Carrier Billing
Know Your Customer (KYC) requirements apply to pay by phone casinos just as they do to any other gambling site operating under a reputable license. The difference is the timing and the friction. When you deposit via card or bank transfer, the casino often has your verified identity already linked to the payment method. With phone deposits, you’re essentially anonymous at the point of transaction. Your carrier knows who you are, but the casino only has a phone number. This creates a verification gap that must be filled before any withdrawal can occur.
The typical KYC process at these casinos requires you to submit government-issued photo ID, proof of address dated within the last three months, and sometimes a screenshot of your phone bill showing the recent deposit transaction. This last requirement is unique to pay by phone casinos and adds an extra step that other payment methods don’t demand. You’re proving not just who you are, but that you actually made the deposit you claim to have made. It’s a double verification that can add 24-48 hours to your first withdrawal, minimum.
Some casinos have started implementing a tiered verification system. Small deposits under A$50 might pass with minimal checks, while larger amounts trigger the full KYC process. This sounds player-friendly until you realize it’s just risk management. The casino is betting that most phone depositors will lose their small deposits before hitting the verification threshold. For the players who do win big, the verification process becomes a speed bump designed to encourage reverse withdrawals (where you cancel your cash-out and gamble the winnings back). It’s a cynical numbers game, and the verification delay is part of the house edge.
Best Live Casino Online Australia 2026: The Only Guide That Doesn’t Treat You Like a Fresh Fish
The Tax Question Nobody Wants to Answer
Australia’s tax treatment of gambling winnings is refreshingly simple for recreational players: you don’t pay tax on winnings. This applies regardless of whether you deposited via phone, bank transfer, or a bag of coins. The Australian Taxation Office (ATO) considers gambling winnings a windfall, not assessable income, as long as you’re playing recreationally. The moment gambling becomes your primary source of income or a business activity, the taxman comes knocking. But for the vast majority of players using pay by phone casinos, this is a non-issue.
However, the carrier billing creates an unusual paper trail. Your phone bill will show deposits to “Mobile Payment Services” or a similar generic descriptor, not the casino’s name. This might seem like a privacy feature, but it’s actually just the carrier’s standard billing practice. The ATO doesn’t typically audit phone bills for gambling transactions, but the money trail exists if anyone ever cares to follow it. For the average player, this is irrelevant. For anyone with complex tax affairs or business interests, it’s another data point in a financial life that’s already complicated enough.
The offshore nature of most pay by phone casinos adds another layer of complexity. While winnings are tax-free for recreational players, the movement of funds to and from offshore entities can trigger reporting requirements for banks and carriers. If you’re making regular large deposits via phone, your carrier might file a suspicious activity report. Not because you’re doing anything illegal, but because their compliance systems are designed to flag unusual patterns. Your casual gambling habit gets swept up in anti-money laundering protocols designed for much larger fish.
The Future: What 2026 Might Actually Bring
The pay by phone method in Australia is likely to evolve in three directions, none of which are particularly exciting. First, transaction limits will probably increase as carriers become more comfortable with the risk profile. This will make the method slightly more useful for serious players but will also increase the potential for harm. Second, more casinos will offer the method as standard, which means more competition for your deposits and potentially better terms. Third, regulatory scrutiny will increase, possibly leading to mandatory spending alerts or cooling-off periods for phone deposits.
The ACMA has been quietly building a case for stricter regulation of carrier billing for gambling. Their 2024 discussion paper hinted at mandatory transaction limits, real-time spending notifications, and possibly even a centralised registry of gambling transactions across all payment methods. If implemented, these measures would make pay by phone casinos significantly less convenient but potentially safer. The industry is lobbying hard against these proposals, arguing that they would simply drive players to less regulated payment methods like cryptocurrency.
Open Banking and the New Payments Platform (NPP) might also disrupt the pay by phone model. Real-time bank transfers via PayTo are becoming more common and offer the same instant deposit speed without the carrier as middleman. If casinos adopt PayTo widely, the pay by phone method could become redundant within a few years. The carrier billing model is a relic of an era when bank transfers took days and e-wallets required separate signups. In a world of instant, free bank transfers, its convenience advantage is rapidly eroding.
Do pay by phone deposits affect my credit score?
No. Carrier billing for gambling deposits is not reported to credit bureaus in Australia. However, if you fail to pay your phone bill (including gambling charges), the resulting debt can be listed on your credit report after it goes to collections. The gambling transaction itself is invisible to lenders, but the unpaid bill is not.
Can I set deposit limits specifically for phone payments?
Some casinos allow you to set payment-method-specific limits, but most don’t. You’ll need to set a general deposit limit for your account, which applies to all payment methods. Your carrier may also allow you to block carrier billing transactions entirely through your account settings, which is the most effective way to control spending via this method.
The real issue with pay by phone casinos in 2026 isn’t the technology or the regulations. It’s the fundamental mismatch between what the method offers and what players actually need. It’s a deposit-only solution in a world that demands two-way financial flexibility. It’s a low-limit tool in an industry that profits from high-volume play. And it’s a convenience product that adds complexity at the exact moment you need simplicity most: when you’re trying to get your money back. The carriers will keep offering it because it’s profitable. The casinos will keep promoting it because it works. And players will keep using it because sometimes, the path of least resistance is the only path they can see.
Best Pokies in Adelaide 2026: A Cynic’s Guide to Not Losing Your Shirt
But here’s the thing about paths of least resistance: they usually lead somewhere you didn’t intend to go. The A$20 deposit that seemed so harmless on Tuesday night becomes a A$200 phone bill by Friday. The “quick session” turns into a three-hour spiral. And the withdrawal you thought would be simple becomes a week-long odyssey through verification portals and customer service chatbots. The method is designed to make the first step easy. Everything after that is your problem.
Minimum Deposit Casino Australia 2026: The Math Behind the “Budget” GambleThe real friction point isn’t the deposit. It’s the inevitable moment you win something and realize you need to set up a Skrill account you never wanted. That’s when the “convenience” reveals itself as a one-way valve. The carrier got their money instantly. The casino got your action. You got a pending withdrawal request and a request to upload a photo of your driver’s license. The system is optimized for one direction, and it’s not the direction where money flows back to you.
Consider the actual user experience at 2 AM on a Sunday. You deposit A$30 via your Optus prepaid balance to chase a bonus on some new pokie. You win A$150. Great. Now what? You navigate to the withdrawal page, select bank transfer, enter your BSB and account number, and wait. The casino’s finance team doesn’t work weekends. Your request sits in a queue until Monday morning. Then it takes 24-48 hours to process. Then another 1-3 business days for the bank transfer to clear. By the time you see that A$150, it’s Thursday, and you’ve already forgotten what you were going to spend it on. The deposit took 3 seconds. The withdrawal takes a week. That’s the asymmetry you’re signing up for.
The Prepaid vs. Postpaid Divide
There’s a critical difference in how this payment method affects you depending on whether you’re on a prepaid or postpaid plan, and most guides gloss over it entirely. For postpaid users, the deposit is essentially a short-term loan from your carrier. The charge appears on your next bill, giving you a brief window before the money actually leaves your bank account. This creates a peculiar psychological effect: the gambling happens now, but the financial consequence is deferred. It’s the same temporal disconnect that makes credit cards dangerous for impulsive spenders, just on a smaller scale.
Prepaid users face a different reality. The money is deducted immediately from your available credit. There’s no deferral, no grace period. If you have A$50 in credit and deposit A$30 to a casino, you’re left with A$20 for calls, texts, and data until you top up again. This creates a hard, tangible limit that postpaid users don’t experience. The prepaid model is actually more honest about the transaction: you’re swapping phone credit for casino credit, and both are finite resources that deplete in real time. There’s a certain brutal clarity to it that the postpaid system lacks.
The carrier’s perspective differs too. For postpaid users, they’re extending a micro-credit facility with built-in fraud detection. For prepaid users, they’re simply facilitating a balance transfer. The risk profile is different, which is why some carriers impose stricter limits on prepaid transactions. If you’re trying to figure out why your A$20 deposit was rejected when your mate’s identical deposit went through, the answer might be sitting in the fine print of your respective plans. The system treats you differently based on how you pay your phone bill, which is a level of nuance that most casino marketing materials conveniently ignore.
Why do some casinos reject pay by phone deposits under A$10?
The processing cost for the casino is fixed regardless of transaction size. A A$5 deposit might cost the casino A$0.50 in carrier fees, which represents a 10% margin hit. For very small transactions, the economics don’t work. Most casinos set a minimum of A$10 or A$20 to ensure the deposit covers their processing costs and still leaves room for the house edge to do its work. It’s not about protecting you from small bets; it’s about protecting their margins.
Can I use pay by phone to deposit at multiple casinos in one day?
Technically yes, but practically you’ll hit carrier-imposed limits quickly. Most carriers cap daily transactions at A$100-A$200 across all merchants. Once you hit that ceiling, you’re done until the next billing cycle. Some casinos also implement their own daily deposit limits for this method, typically around A$300. The system is designed for occasional, small deposits, not for funding a serious gambling session across multiple platforms.
The carrier’s fraud detection algorithms also watch for unusual patterns. Multiple deposits to different gambling merchants within a short timeframe can trigger a temporary block. This is ostensibly for your protection, but it’s really about the carrier managing their risk exposure. If you suddenly start making five A$20 deposits to five different casinos in an hour, the system flags it as potential account compromise. Your gambling habit gets treated like a security breach, which tells you everything you need to know about how the industry really views this payment method.
Best Aussie Pokies Online Australia 2026: A Cynic’s Guide to Not Losing Your Shirt
And that’s the thing nobody tells you when you’re setting up that first deposit. The convenience is real, but it comes with invisible tripwires. The carrier is watching, the casino is calculating, and you’re somewhere in the middle, thinking you’ve found a clever workaround. The only thing you’ve actually found is a different set of constraints. The money still flows one way, the house still has the edge, and your phone bill still arrives at the end of the month with a line item that reads like a confession.
The Verification Dance: KYC Meets Carrier Billing
Know Your Customer (KYC) requirements apply to pay by phone casinos just as they do to any other gambling site operating under a reputable license. The difference is the timing and the friction. When you deposit via card or bank transfer, the casino often has your verified identity already linked to the payment method. With phone deposits, you’re essentially anonymous at the point of transaction. Your carrier knows who you are, but the casino only has a phone number. This creates a verification gap that must be filled before any withdrawal can occur.
The typical KYC process at these casinos requires you to submit government-issued photo ID, proof of address dated within the last three months, and sometimes a screenshot of your phone bill showing the recent deposit transaction. This last requirement is unique to pay by phone casinos and adds an extra step that other payment methods don’t demand. You’re proving not just who you are, but that you actually made the deposit you claim to have made. It’s a double verification that can add 24-48 hours to your first withdrawal, minimum.
Some casinos have started implementing a tiered verification system. Small deposits under A$50 might pass with minimal checks, while larger amounts trigger the full KYC process. This sounds player-friendly until you realize it’s just risk management. The casino is betting that most phone depositors will lose their small deposits before hitting the verification threshold. For the players who do win big, the verification process becomes a speed bump designed to encourage reverse withdrawals (where you cancel your cash-out and gamble the winnings back). It’s a cynical numbers game, and the verification delay is part of the house edge.
Best Live Casino Online Australia 2026: The Only Guide That Doesn’t Treat You Like a Fresh Fish
The Tax Question Nobody Wants to Answer
Australia’s tax treatment of gambling winnings is refreshingly simple for recreational players: you don’t pay tax on winnings. This applies regardless of whether you deposited via phone, bank transfer, or a bag of coins. The Australian Taxation Office (ATO) considers gambling winnings a windfall, not assessable income, as long as you’re playing recreationally. The moment gambling becomes your primary source of income or a business activity, the taxman comes knocking. But for the vast majority of players using pay by phone casinos, this is a non-issue.
However, the carrier billing creates an unusual paper trail. Your phone bill will show deposits to “Mobile Payment Services” or a similar generic descriptor, not the casino’s name. This might seem like a privacy feature, but it’s actually just the carrier’s standard billing practice. The ATO doesn’t typically audit phone bills for gambling transactions, but the money trail exists if anyone ever cares to follow it. For the average player, this is irrelevant. For anyone with complex tax affairs or business interests, it’s another data point in a financial life that’s already complicated enough.
The offshore nature of most pay by phone casinos adds another layer of complexity. While winnings are tax-free for recreational players, the movement of funds to and from offshore entities can trigger reporting requirements for banks and carriers. If you’re making regular large deposits via phone, your carrier might file a suspicious activity report. Not because you’re doing anything illegal, but because their compliance systems are designed to flag unusual patterns. Your casual gambling habit gets swept up in anti-money laundering protocols designed for much larger fish.
The Future: What 2026 Might Actually Bring
The pay by phone method in Australia is likely to evolve in three directions, none of which are particularly exciting. First, transaction limits will probably increase as carriers become more comfortable with the risk profile. This will make the method slightly more useful for serious players but will also increase the potential for harm. Second, more casinos will offer the method as standard, which means more competition for your deposits and potentially better terms. Third, regulatory scrutiny will increase, possibly leading to mandatory spending alerts or cooling-off periods for phone deposits.
The ACMA has been quietly building a case for stricter regulation of carrier billing for gambling. Their 2024 discussion paper hinted at mandatory transaction limits, real-time spending notifications, and possibly even a centralised registry of gambling transactions across all payment methods. If implemented, these measures would make pay by phone casinos significantly less convenient but potentially safer. The industry is lobbying hard against these proposals, arguing that they would simply drive players to less regulated payment methods like cryptocurrency.
Open Banking and the New Payments Platform (NPP) might also disrupt the pay by phone model. Real-time bank transfers via PayTo are becoming more common and offer the same instant deposit speed without the carrier as middleman. If casinos adopt PayTo widely, the pay by phone method could become redundant within a few years. The carrier billing model is a relic of an era when bank transfers took days and e-wallets required separate signups. In a world of instant, free bank transfers, its convenience advantage is rapidly eroding.
Do pay by phone deposits affect my credit score?
No. Carrier billing for gambling deposits is not reported to credit bureaus in Australia. However, if you fail to pay your phone bill (including gambling charges), the resulting debt can be listed on your credit report after it goes to collections. The gambling transaction itself is invisible to lenders, but the unpaid bill is not.
Can I set deposit limits specifically for phone payments?
Some casinos allow you to set payment-method-specific limits, but most don’t. You’ll need to set a general deposit limit for your account, which applies to all payment methods. Your carrier may also allow you to block carrier billing transactions entirely through your account settings, which is the most effective way to control spending via this method.
The real issue with pay by phone casinos in 2026 isn’t the technology or the regulations. It’s the fundamental mismatch between what the method offers and what players actually need. It’s a deposit-only solution in a world that demands two-way financial flexibility. It’s a low-limit tool in an industry that profits from high-volume play. And it’s a convenience product that adds complexity at the exact moment you need simplicity most: when you’re trying to get your money back. The carriers will keep offering it because it’s profitable. The casinos will keep promoting it because it works. And players will keep using it because sometimes, the path of least resistance is the only path they can see.
Best Pokies in Adelaide 2026: A Cynic’s Guide to Not Losing Your Shirt
But here’s the thing about paths of least resistance: they usually lead somewhere you didn’t intend to go. The A$20 deposit that seemed so harmless on Tuesday night becomes a A$200 phone bill by Friday. The “quick session” turns into a three-hour spiral. And the withdrawal you thought would be simple becomes a week-long odyssey through verification portals and customer service chatbots. The method is designed to make the first step easy. Everything after that is your problem.
Minimum Deposit Casino Australia 2026: The Math Behind the “Budget” Gamble
独自に開発した
タイピングソフトを販売しております。
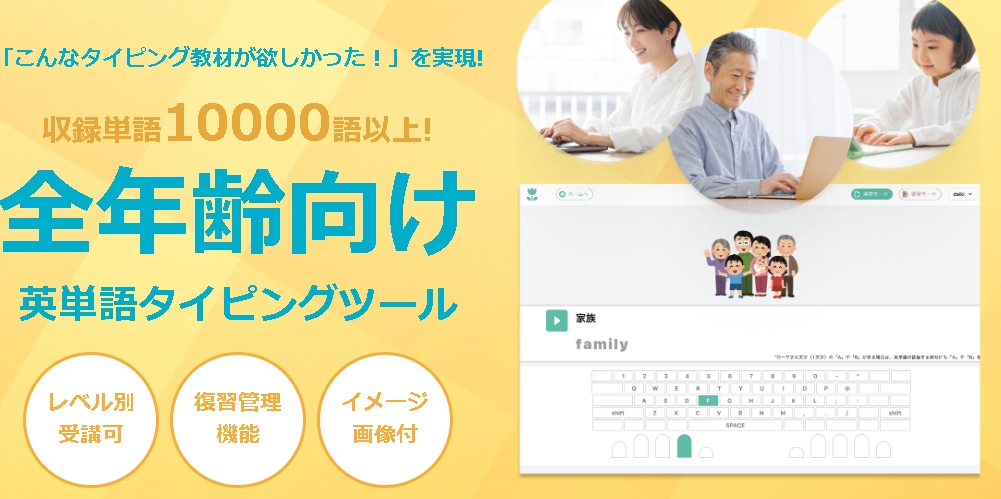
単語学習、聞き取り学習、タイピング練習はもちろん。
できなかった部分だけを重点的に学習できるように復習機能もついています。
また、中1レベルからTOEIC900点クラスまで網羅している為
無料お試し版がご利用いただけますので