Casinos That Accept MiFinity Australia 2026: A Veteran’s Guide to Not Losing Your Shirt
Forget the glossy banners and the promises of instant riches. If you’re looking for casinos that accept MiFinity in Australia for 2026, you’re likely a player who values discretion and speed over flashy marketing. MiFinity has carved a niche as a reliable e-wallet for online gambling, offering a buffer between your bank and the casino’s ledger. The landscape in 2026 is more competitive than ever, with operators scrambling to offer seamless payment experiences. But let’s be clear: the presence of MiFinity on a cashier page is a baseline requirement, not a badge of honour. The real test lies in the fine print—the withdrawal limits, the processing times, and whether the casino actually respects your time once you’ve decided to cash out.
The Australian market, despite its regulatory complexities, has seen a steady adoption of e-wallets like MiFinity. Players are tired of the 3-5 business day wait for bank transfers and the intrusive nature of direct card transactions. MiFinity offers a middle ground: a dedicated account that can be funded via various methods, including local bank transfers and cards, which then acts as a single point of deposit and withdrawal across multiple casinos. This separation of finances is a practical benefit, not a “feature.” It’s basic digital hygiene in an industry where your bank statement might otherwise read like a catalogue of questionable decisions. The convenience is real, but it comes with its own set of considerations, primarily around fees and verification steps that many guides conveniently omit.
Why MiFinity? The Pragmatic Case for an E-Wallet Buffer
At its core, MiFinity is a payment processing solution licensed by the Financial Conduct Authority (FCA) in the UK, which gives it a layer of legitimacy that many casino-specific wallets lack. For Australian players, the primary appeal isn’t the brand name—it’s the functionality. Deposits are typically instant, and more importantly, withdrawals are often processed back to the MiFinity account within 24 hours, a stark contrast to the glacial pace of direct bank transfers. The casino sends the funds to your e-wallet, and from there, you have control: you can leave it for future play, spend it online elsewhere, or transfer it to your bank account at your leisure. This control is the actual value proposition, not some abstract notion of “security.”
Consider the math. A standard bank wire withdrawal from an offshore casino to an Australian bank might incur a flat fee of $25-$50 AUD and take 5-7 business days. A MiFinity withdrawal, assuming the casino doesn’t tack on its own fee, might cost you a small percentage or a fixed fee of a few euros to move money from the wallet to your bank. For a player making regular withdrawals of, say, $500 AUD, the difference in speed and potential fee savings over a year is significant. It’s not about getting rich; it’s about not bleeding money on unnecessary charges and having your funds available when you want them. The “free” movement of money is an illusion—there’s always a cost somewhere, but MiFinity often makes that cost more transparent and manageable.
The integration process for casinos is also relatively straightforward, which is why more platforms are adding it. It requires the operator to partner with MiFinity and configure their cashier system. The presence of the MiFinity logo on a casino’s banking page is a signal that they’ve invested in offering a modern payment option. However, it tells you nothing about the casino’s fairness, game selection, or customer support. It’s a payment method, not a quality seal. Players often make the mistake of assuming that a sophisticated payment page equals a sophisticated casino. It doesn’t. It just means they have a slightly better IT department for handling money.
The Australian Regulatory Reality: A Necessary Detour
Before we discuss specific operators, a dose of reality is required. The Interactive Gambling Act 2001 (IGA) and its amendments make it illegal for online casinos to offer real-money interactive gambling services to people in Australia. This doesn’t stop Australian players from accessing offshore casinos—that’s a separate legal grey area for the individual—but it means there are no locally licensed and regulated online casinos. Every single operator you’ll find accepting Australian players and MiFinity is, by definition, an offshore entity licensed in jurisdictions like Curaçao, Malta (MGA), Gibraltar, or Kahnawake.
This has direct implications for you. If a dispute arises, your recourse is with the foreign regulator, not an Australian court. The Australian Communications and Media Authority (ACMA) can and does block access to illegal gambling sites, but enforcement is a game of whack-a-mole. The practical takeaway? Your due diligence is paramount. A MiFinity-accepting casino licensed by the Malta Gaming Authority (MGA) offers a stronger dispute resolution pathway than one licensed solely in Curaçao. The payment method is a constant; the regulatory safety net is a variable. Don’t confuse the two. The presence of MiFinity doesn’t immunize you from the risks of playing on an unregulated platform.
Furthermore, banks and credit card companies in Australia are increasingly vigilant about transactions flagged as gambling-related. Using MiFinity can sometimes help here, as the transaction on your bank statement may show as a transfer to MiFinity rather than a direct payment to “XYZ Casino Ltd.” This isn’t foolproof, and it’s not a reason to lie to your bank, but it adds a layer of transactional privacy that some players find valuable. The point is not concealment, but managing the flow of information in a way that suits your personal preferences. It’s a tool, and like any tool, its usefulness depends on how and why you’re using it.
What Makes a MiFinity Casino Worth Your Time? Beyond the Logo
So, a casino accepts MiFinity. Congratulations. Now what? The real evaluation begins. First, look at the withdrawal limits and processing times specifically for MiFinity. Some casinos list e-wallet withdrawals as “up to 24 hours,” but that’s the processing time on their end. What are the daily, weekly, and monthly limits? A casino might process your MiFinity withdrawal in 1 hour but cap it at $1,000 AUD per week, which is useless if you’ve just hit a decent win. You need to find the specific terms in the banking or FAQ section, not just trust the marketing bullet point.
Second, check for fees. The casino might not charge a fee for MiFinity withdrawals, but MiFinity itself will have fees for certain transactions, like currency conversion (EUR to AUD) or transferring funds from the wallet to your bank. These fees are publicly available on MiFinity’s own website. A savvy player does the full cost calculation: deposit fee + potential conversion fee + withdrawal fee. Sometimes, a method with a small upfront fee but no conversion costs is cheaper overall. The casino’s “no fees” claim is only one piece of the financial puzzle.
Third, verify the verification process. MiFinity itself requires identity verification (KYC). When you link it to a casino, you might face a two-stage verification: once with MiFinity, and again with the casino if their internal risk systems flag your account. This is standard practice, but the speed and clarity of the casino’s verification team matter. A casino that takes 48 hours to approve your documents negates the speed advantage of using an e-wallet in the first place. Look for reviews or forum posts that mention the actual verification experience, not just the payment method list.
Operator Evaluation: A Framework, Not a Recommendation
Given the regulatory constraints, I cannot provide a ranked list of specific casinos. Instead, here is a framework for evaluating any operator that claims to accept MiFinity in Australia. Use this as a checklist. If an operator fails on multiple points, it doesn’t matter how many payment methods they support.
| Evaluation Criterion | What to Look For (Red Flags in Parentheses) | Why It Matters |
|---|---|---|
| License Jurisdiction | Prefer MGA, UKGC, Gibraltar, Kahnawake. Curaçao is common but offers weaker player protection. (No license information displayed at all) | Determines your recourse in a dispute. A Curaçao license is better than nothing, but not by much. |
| MiFinity Withdrawal Terms | Specific processing time (e.g., “within 12 hours”), clear daily/weekly/monthly limits, stated fee policy. (Vague “fast withdrawals” with no details) | Directly impacts your access to winnings. Vague terms are a major red flag. |
| KYC Verification Speed | Look for user reports on verification time. Ideal is under 24 hours. (Multiple reports of delays exceeding 72 hours) | A slow verification process defeats the purpose of using a fast e-wallet. |
| Game Fairness & RTP | Presence of audits from eCOGRA, iTech Labs, GLI. Published Return to Player (RTP) percentages for games. (No mention of independent testing) | Ensures games aren’t rigged. An e-wallet can’t protect you from unfair software. |
| Customer Support Responsiveness | Test with a pre-registration query. Check for 24/7 live chat and email support with stated response times. (Only a contact form, no live chat) | When a payment issue arises at 3 AM, you need someone to talk to, not a bot. |
This table is your primary tool. Any “top list” you find online is likely driven by affiliate commissions, not player welfare. The operator paying the highest commission gets the top spot. Your evaluation should be cold, methodical, and based on verifiable facts, not persuasive copy. The presence of MiFinity is a filter, not a destination. It narrows the field; it doesn’t declare a winner.
MiFinity vs. The Competition: A Cost and Speed Analysis
How does MiFinity stack up against other e-wallets commonly available to Australian players, like Skrill, Neteller, and ecoPayz? The differences are often in the details, not the headline features. All offer a similar buffer between your bank and the casino. The devil is in the fees and the specific integrations each casino has chosen to enable.
| Feature | MiFinity | Skrill / Neteller | ecoPayz |
|---|---|---|---|
| Typical Deposit Fee | Often 0% from casino side; MiFinity may charge for funding methods. | Many casinos charge 2-5% for Skrill/Neteller deposits. This is a major hidden cost. | Variable, often 0-2%. |
| Withdrawal Processing | Generally 0-24 hours from casino side. | Can be instant to 48 hours, but VIP status often required for speed. | Typically 24-48 hours. |
| Currency Conversion | Transparent fee structure (check their site). | Often includes a 3.99% foreign exchange fee on top of other charges. | Competitive but variable. |
| Australian Bank Transfer | Available, with associated fees and times. | Available, but often slower and more expensive for AUD. | Available. |
| Gambling Transaction Visibility | Statement shows “MiFinity” transfer. | Statement shows “Skrill” or “Neteller.” | Statement shows “ecoPayz.” |
The critical point from this comparison is the deposit fee. A casino that charges a 5% fee on Skrill deposits but 0% on MiFinity deposits is effectively making MiFinity the cheaper option by a wide margin, even if MiFinity’s own internal fees are slightly higher. Always calculate the total cost of the transaction journey. The “best” payment method is the one that gets your money to the casino and back to your pocket with the least total friction and cost. For many Australian players in 2026, MiFinity hits that sweet spot, but it’s not automatic. You must do the math for your specific play pattern.
Another factor is casino preference. Some operators have exclusive deals with certain e-wallets, offering faster processing or lower minimums for one method over another. This is a marketing tactic to drive volume to a preferred partner. It benefits you only if you notice it. A casino might list MiFinity but default to processing Skrill withdrawals faster for “VIP” players. Read the terms for each payment method individually; don’t assume they’re all treated equally.
The “VIP” Program and Your MiFinity Account: A Cynical Look
Many casinos will try to upsell you on their “VIP” program, promising higher withdrawal limits and faster payouts for loyal players. Let’s dissect this with MiFinity in mind. A standard MiFinity account has its own transaction limits, which are separate from the casino’s limits. If the casino raises your weekly withdrawal limit from $5,000 to $20,000 AUD as a “VIP,” but your MiFinity account has a monthly outgoing transfer limit of €10,000 (roughly $16,500 AUD), you’ve hit a new bottleneck. The casino’s “generous” offer is partially offset by the e-wallet’s own constraints.
The “free” perks of a VIP program—like a dedicated account manager—are often just a more efficient way to handle your complaints when you inevitably have one. It’s not a friendship; it’s a customer service tier. The real VIP benefit is mathematical: better conversion rates on loyalty points, higher cashback percentages, and those increased limits. But these benefits are earned through volume. If you’re not depositing and losing (or winning and re-depositing) significant sums, you’re not getting the meaningful perks. The program is designed to reward the house’s best customers, which, in gambling terms, often means the biggest losers over time.
When evaluating a casino’s VIP offer in the context of MiFinity, ask one question: do the increased limits and speeds apply specifically to MiFinity withdrawals, or just to bank wires? Sometimes, the “instant withdrawal” VIP perk only applies to crypto or specific methods, not e-wallets. The marketing is deliberately ambiguous. Clarify this before you chase a VIP status. The promise of speed is worthless if it’s attached to a payment method you don’t use.
Best Pokie Machine to Play Australia 2026: A Cynic’s Guide to Not Losing Your Shirt
New Casinos and MiFinity: Proceed with Caution
The allure of a new casino is understandable—fresh bonuses, modern interfaces, and the hope of finding a hidden gem. When a new casino launches with MiFinity support, it’s often a sign they’ve invested in their payment infrastructure from the start. However, it’s also a sign they need to attract depositors quickly. New casinos are inherently riskier. They have no track record of payouts, their customer support teams are untested, and their financial stability is unknown.
A new casino offering a 200% “welcome gift” on your first MiFinity deposit is not being generous. They are front-loading a marketing budget to acquire you as a customer. The terms of that bonus—the wagering requirements, the maximum bet limits, the game restrictions—are where the real math lies. A 200% bonus with a 60x wagering requirement on (deposit + bonus) is mathematically almost impossible to clear on most games. It’s a hook, not a gift. The casino knows that most players will fail to clear it and will play with their original deposit, which is what they actually want.
Wishwin Casino Free Spins 2026: The Cold Math Behind the “Gift”
If you choose to try a new MiFinity casino, do it with extreme caution. Deposit the absolute minimum required to test the system. Make a small deposit, play a few rounds, and then request a withdrawal. This tests the entire cycle: deposit speed, game functionality, and most importantly, withdrawal processing and verification. If they pass this basic test, you can consider a larger deposit. If they fail—if the withdrawal is delayed, if support is unresponsive—walk away. Your small test deposit is the cost of due diligence, and it’s far cheaper than depositing a large sum and discovering problems when you try to cash out.
Security and Fraud: Protecting Your MiFinity Wallet
Using MiFinity adds a layer of security, but it also adds a layer of responsibility. Your MiFinity account is a financial account. Treat it with the same care as your bank login. Enable two-factor authentication (2FA) immediately. Use a unique, strong password that you don’t use for any casino or other site. The biggest risk isn’t a casino hacking MiFinity; it’s a phishing attack or a compromised device giving a fraudster access to your wallet.
Be wary of any casino that asks you to deposit via a third-party MiFinity account or to send funds directly to a personal wallet address. Legitimate transactions are always between your verified MiFinity account and the casino’s official merchant account. If a support agent suggests an “alternative” deposit method involving a personal transfer, it’s a scam. Period. Also, regularly review your MiFinity transaction history for any unfamiliar activity. The convenience of an e-wallet is negated if you don’t monitor it.
From the casino’s side, they have their own fraud preventionsystems. They use encryption, tokenization, and fraud detection algorithms to protect their side of the transaction. But these systems are not infallible. A data breach at the casino level could expose your personal information, even if your financial details are tokenized. This is why the choice of a reputable, licensed operator is so critical. A casino with a strong regulatory oversight is more likely to have robust data protection protocols. A fly-by-night operation in a jurisdiction with lax data laws is a gamble in itself, and not the fun kind.
The practical step here is to compartmentalize. Use a dedicated email address for your MiFinity and casino accounts, separate from your primary personal or work email. Use a password manager. Don’t reuse credentials. These are basic digital hygiene practices, but they are often ignored in the convenience of signing up for a new account. The few minutes it takes to set up properly can save you from a world of headache. Your MiFinity wallet is a tool for managing your gambling finances, not a toy. Treat it with the seriousness it deserves, because the consequences of lax security are immediate and financially painful.
Wagering Requirements and the MiFinity Withdrawal Trap
Here’s a scenario that plays out daily. A player deposits $100 AUD via MiFinity, claims a “100% match bonus,” and now has $200 to play with. They hit a nice run on slots and their balance climbs to $500. They go to withdraw, only to be told they cannot because they haven’t met the 40x wagering requirement on the bonus amount. That’s $4,000 in bets they need to place before touching a cent. The MiFinity withdrawal speed is irrelevant if the casino holds your funds hostage behind bonus terms you didn’t read. This isn’t a payment method issue; it’s a terms and conditions issue, but it directly impacts your experience with MiFinity withdrawals.
The math is brutal. A 40x wagering requirement on a $100 bonus means $4,000 in total bets. With a typical slot RTP of 96%, the expected loss on that volume of play is around $160. You’re statistically likely to lose your entire bonus and a chunk of your original deposit before you can withdraw. The “free” bonus is a mathematical trap for the undisciplined. When using MiFinity, always check if the bonus is opt-in or automatically applied. Some casinos automatically add the bonus to your deposit, meaning you’re locked in from the moment you fund your account. Opt for no bonus if you want the freedom to withdraw your winnings immediately via MiFinity without wagering constraints.
This is where the cynical veteran’s advice kicks in: ignore the bonus. Take the deposit, play with your own money, and withdraw your winnings via MiFinity as soon as you hit your target. The absence of a bonus means the absence of wagering requirements. Your $500 win is your $500 win, ready to be transferred back to your e-wallet. The casino hates this strategy, which is why they dangle the bonus so prominently. They want you locked into the wagering cycle. Your best move is to refuse the game and play on your own terms.
Mobile Gaming and MiFinity: The On-the-Go Reality
Most gambling in 2026 happens on a phone. MiFinity has a functional mobile app, and most casinos have responsive mobile sites or dedicated apps. The integration works smoothly: you can deposit and request withdrawals from your phone without issue. However, the mobile experience introduces new variables. Document uploads for KYC verification are often easier on a desktop. Trying to photograph your driver’s license and a utility bill through a phone camera, then upload them through a casino’s mobile interface, can be a frustrating exercise in poor UX design. A casino that has a streamlined mobile deposit process but a clunky, multi-step mobile verification process is not truly mobile-friendly.
Also, consider the security of your mobile device. If you use Face ID or fingerprint login for your MiFinity app, that’s a strong layer of security. If you’re using a simple 4-digit PIN, you’re one lost phone away from potential trouble. The convenience of mobile gambling with MiFinity is undeniable, but it requires you to be more vigilant about device security. A lost or stolen phone with an unlocked MiFinity app is a direct financial risk. Enable all available biometric and 2FA security features on both your phone and the app itself. The extra few seconds to authenticate are worth it.
Currency Conversion and the AUD Question
Most offshore casinos operate in EUR or USD. When you deposit AUD via MiFinity, a currency conversion happens. MiFinity will convert your AUD to the casino’s operating currency at the prevailing exchange rate, plus a fee. This fee is often a percentage of the transaction amount, typically between 1% and 3%. On a $1,000 AUD deposit, that’s $10-$30 lost to conversion before you’ve placed a single bet. When you withdraw, the reverse happens: the casino sends EUR or USD to your MiFinity account, which then converts it back to AUD for you to transfer to your bank. You’re paying the conversion fee twice.
This double conversion is a hidden cost that most guides ignore. The total cost of using MiFinity at a EUR-denominated casino is: deposit conversion fee + withdrawal conversion fee + any MiFinity transfer fee to your bank. For a player making frequent, smaller transactions, this can eat a noticeable chunk of their bankroll over time. The solution, if available, is to find a casino that accepts AUD directly. Some offshore operators do accept AUD, which eliminates the conversion fees entirely. If AUD acceptance isn’t an option, factor the estimated conversion cost into your bankroll management. It’s not a reason to avoid MiFinity, but it’s a cost to be aware of and plan for.
How do I find casinos that accept AUD and MiFinity?
Search specifically for “AUD casino” or “Australian dollar casino” combined with your payment method preference. Check the casino’s banking page or FAQ for a list of supported currencies. If AUD is listed, your deposits and withdrawals will be in AUD, avoiding conversion fees. If only EUR or USD are listed, expect the double conversion. This simple check can save you significant money over time.
Is MiFinity safer than using my credit card directly at a casino?
It offers a different type of safety. Using a credit card directly exposes your card details to the casino’s payment processor. MiFinity acts as an intermediary, so the casino never sees your card or bank details—only your MiFinity account identifier. This reduces the risk of your card details being compromised in a casino data breach. However, it adds the responsibility of securing your MiFinity account itself. It’s a trade-off between direct exposure and intermediary risk.
What happens if a casino delays my MiFinity withdrawal?
First, check the casino’s stated processing time and your account verification status. An unverified account is the most common cause of delay. If you’re verified and the stated time has passed, contact customer support with your transaction ID. If they are unresponsive or give vague answers, escalate the issue to the casino’s licensing authority (e.g., MGA, Curaçao). This is where a reputable license pays off. For casinos with no license or a weak one, your options are limited to public forums and complaint sites, which are not guarantees of resolution.
Can I use MiFinity for both deposits and withdrawals at the same casino?
Almost always, yes. Casinos that accept MiFinity for deposits generally allow withdrawals to the same method. However, always verify this on the banking page. A rare few might allow deposits via one method but force withdrawals via another (like bank transfer), which is a major inconvenience and a red flag. The standard practice is method reciprocity, but confirm it before you deposit.
Are there any Australian taxes on gambling winnings made via MiFinity?
For recreational players, gambling winnings in Australia are generally not considered taxable income. The tax is levied on the operators, not the players. However, if you are deemed to be a professional gambler—where gambling is your primary source of income and you operate in a business-like manner—the ATO may view your winnings differently. For the vast majority of players using MiFinity for casual play, this is not a concern. Keep your play recreational, and the taxman stays away.
Slotozen Casino Free Spins 2026: A Veteran’s Guide to the Math Behind the “Gift”
The entire process, from funding your MiFinity wallet to transferring winnings back to your bank, is a series of small, calculated steps. Each step has a cost, a time frame, and a security consideration. The player who understands these mechanics—who sees the conversion fees, the verification hurdles, and the bonus traps for what they are—is the one who navigates the landscape without unnecessary losses. The casino’s interface is designed to make you forget these details, to focus on the games and the flashing lights. Your job is to remember them, to treat the payment process with the same analytical rigor you’d apply to a hand of blackjack. Because in the end, the house edge isn’t just in the games; it’s in the friction of moving your money. And the only person who can minimize that friction is you. The fine print on the MiFinity withdrawal page is written in a font size specifically chosen to discourage reading.It’s a deliberate design choice. They want you focused on the spinning reels, not the spinning numbers of their profit margin. The entire ecosystem, from the casino’s cashier page to MiFinity’s own interface, is optimized for the deposit. The withdrawal is an afterthought, a necessary evil they must provide but certainly don’t want to highlight. Your victory is their loss, and they’ll make you work for it in a thousand small, bureaucratic ways. The font size is just the most honest expression of that principle.
The Future Outlook: MiFinity in the Evolving 2026 Landscape
The payment landscape in iGaming shifts faster than a dealer shuffling a six-deck shoe. By 2026, the integration of MiFinity into Australian-facing casinos has moved from a novelty to a baseline expectation for serious operators. We are seeing a trend where e-wallets are no longer just passive repositories for funds but active participants in the transaction lifecycle. MiFinity has introduced features like instant SEPA transfers and enhanced IBAN support, which, while primarily European features, signal a move towards a more unified global banking standard that even Australian players benefit from indirectly through faster processing times.
The rise of Open Banking APIs is another factor that will likely impact how MiFinity functions. In the near future, the friction of funding the e-wallet itself could be reduced, allowing for direct, real-time bank-to-wallet transfers without the traditional delays of card processing or manual bank transfers. For the Australian market, where banking infrastructure is robust but conservative, this slow trickle of innovation is the only way forward. MiFinity is positioning itself to be compatible with these upcoming PSD3 (Payment Services Directive) frameworks, even if the direct application to non-EU markets is murky. The takeaway for the player is simple: the backend is getting faster, even if the casino’s front-end withdrawal approval process remains stuck in the 1990s.
Crypto integration is the elephant in the room. While MiFinity is not a crypto wallet, many casinos that accept it also accept Bitcoin or Ethereum. We are seeing a hybrid approach where players use MiFinity for the stability of fiat currency and the ease of bank transfers, but might switch to crypto for larger, faster withdrawals if the casino allows it. However, the volatility of crypto makes MiFinity the “boring” but reliable choice for players who want their $500 AUD to still be worth $500 AUD when it hits their bank account. In a market obsessed with the next shiny thing, MiFinity’s refusal to be a crypto exchange is actually its strength. It does one thing—fiat processing—and it does it with a level of regulatory compliance that most crypto-native payment processors simply cannot match.
The regulatory pressure from the ACMA will likely increase, leading to more domain blocks and payment gateway interventions. This means that the ability of MiFinity to process transactions to and from offshore gambling sites could face headwinds. However, as an FCA-regulated entity, MiFinity has the legal standing to argue for the legitimacy of its core business services, distinct from the gambling activities of its merchants. This separation is crucial. As long as MiFinity treats gambling transactions as a legitimate category of commerce—subject to strict AML and CTF checks—it should survive the regulatory tightening that will inevitably crush smaller, less compliant payment processors. For the Australian player, this means MiFinity is likely to remain a viable option longer than some of its smaller competitors who lack the regulatory armor.
The user interface of these e-wallets is also evolving. We are moving away from the clunky, desktop-first designs of the early 2010s towards mobile-native experiences. MiFinity’s app updates in late 2025 focused heavily on biometric authentication and one-tap withdrawals. This is not just about convenience; it is about security. The easier it is for a legitimate user to authenticate a transaction, the harder it is for a fraudster to use stolen credentials without triggering a biometric mismatch. The future of gambling payments is biometric. Your face or your fingerprint is the new password. Casinos that force you to jump through hoops of 2FA codes and email confirmations for every withdrawal are living in the past. MiFinity is dragging them, kicking and screaming, into a future where security does not have to mean inconvenience.
What are the typical fees for using MiFinity in Australia?
Fees vary based on your funding method and the transaction type, but generally, MiFinity charges a small percentage for card deposits and a flat fee for bank transfers. Withdrawals from the casino to MiFinity are usually free on the casino’s end, but moving funds from MiFinity to your Australian bank account incurs a fee, typically around 1-2% of the amount or a fixed Euro-based fee. Always check the “Fees” section on the MiFinity website before transacting, as these can change and are often the difference between a profitable session and a break-even one.
Can I reverse a casino withdrawal back to MiFinity?
This is a feature known as “reverse withdrawal,” and it is a trap. Some casinos allow you to cancel a pending withdrawal and put the funds back into your playing balance. While technically possible in some systems, it is a practice designed to make you lose the money back to the house. If you have requested a withdrawal via MiFinity, let it process. Do not cancel it. The urge to play with “just a little bit more” is exactly what the casino is counting on. Once the money is in your MiFinity wallet, it is safe. Keep it there.
Is MiFinity anonymous?
No. MiFinity is a fully regulated e-money institution. They know who you are, and they require KYC (Know Your Customer) documentation to operate your account. The casino also knows who you are. The only anonymity is relative: your bank statement shows a transfer to “MiFinity,” not “Lucky Spins Casino.” This is privacy by obscurity, not true anonymity. If you are looking for anonymous gambling, e-wallets are not the answer; they are simply a layer of separation.
How long does MiFinity verification take?
Initial verification of your MiFinity account can take 24 to 48 hours, depending on the volume of applications and the clarity of the documents you submit. Once verified, subsequent transactions are usually instant or near-instant. However, if your account is flagged for a manual review—which can happen with large or unusual transactions—it can take longer. The advice is to verify your account well before you plan to make a large withdrawal. Do not wait until you have won big to start the ID check process.
What if my bank blocks the transfer from MiFinity?
Some Australian banks are hostile to gambling-related transactions, even indirect ones. If your bank flags a transfer from MiFinity as suspicious, they may freeze the transaction or your account temporarily. This is more common with smaller, digital-only banks that have aggressive fraud algorithms. The workaround is to use a major, traditional bank that is accustomed to processing international transfers, or to use the MiFinity prepaid card if available in your region, which allows you to spend the funds directly rather than transferring them to a bank account. It is a hassle, but it is the reality of banking in a market where online gambling is a legal grey area.
The ecosystem of online gambling payments is a constant tug-of-war between convenience and control. MiFinity offers a decent balance, but it is not a magic wand. It is a tool that requires you to understand its limitations and its costs. The casinos that accept it are not doing you a favour; they are simply plugging into a payment network that their competitors also use. Your loyalty should be to your bankroll, not to a payment logo. Use MiFinity because it makes financial sense for your specific play style, not because it was the first option on the list. And always, always read the fine print on the withdrawal page. The font size is small for a reason.The font size is small for a reason. It’s a calculated design choice, a tiny act of passive aggression from the casino’s UX team. They want your eyes on the jackpot ticker, not the fee schedule. The entire interface is a carefully constructed illusion of generosity, built on a foundation of mathematical certainty. Your job is to see through it, to treat every “feature” as a potential cost center. The “free” bonus, the “instant” withdrawal, the “VIP” treatment—all are marketing terms for standard operational procedures. The real value is found in the gaps between the promises, in the cold, hard numbers of wagering requirements and conversion fees. The player who understands this is the one who walks away with more than they came with, or at least loses less than they expected. The casino’s profit margin is baked into every pixel of that withdrawal page, from the colour of the “Confirm” button to the opacity of the terms link. Your only defence is a healthy dose of cynicism and a calculator. The house always wins in the long run, but in the short run, a well-informed player can at least make them work for it. And that’s the only victory available in a game designed for you to lose.The player who understands this is the one who walks away with more than they came with, or at least loses less than they expected. The casino’s profit margin is baked into every pixel of that withdrawal page, from the colour of the “Confirm” button to the opacity of the terms link. Your only defence is a healthy dose of cynicism and a calculator. The house always wins in the long run, but in the short run, a well-informed player can at least make them work for it. And that’s the only victory available in a game designed for you to lose.
The regulatory landscape for MiFinity in Australia is not static. It’s a moving target, shaped by the ACMA’s enforcement actions and the broader global push for stricter anti-money laundering (AML) controls. In 2026, we’re seeing a more sophisticated approach from regulators. Instead of just blocking domains, they’re putting pressure on payment gateways and financial institutions to identify and restrict gambling-related transactions. This means that even if a casino accepts MiFinity, your ability to fund that MiFinity account via an Australian bank transfer might become more complicated. Banks are being asked to implement more robust transaction monitoring systems, which can lead to legitimate gambling deposits being flagged and delayed. The irony is thick: the very system designed to prevent financial crime can also create significant friction for law-abiding players simply trying to move their own money.
MiFinity’s response to this pressure has been to double down on its compliance framework. They are investing in more advanced fraud detection algorithms and working more closely with their casino partners to ensure that the funds flowing through their system are clean. For the player, this translates to potentially more stringent checks on larger transactions. If you suddenly deposit a sum that is significantly higher than your usual pattern, expect a request for additional documentation. This isn’t the casino being difficult; it’s MiFinity fulfilling its regulatory obligations. The inconvenience is real, but it’s the price of operating in a regulated financial ecosystem. The alternative—a completely unregulated, anonymous payment channel—is a recipe for fraud and theft.
The future of MiFinity in Australia will also be shaped by the competition. Other e-wallets are vying for the same market share, and they’re all adapting to the same regulatory pressures. The winner will be the one that can offer the best combination of speed, cost, and reliability while navigating the complex compliance requirements. MiFinity has a head start due to its early adoption in the iGaming space, but it’s not resting on its laurels. The company is actively expanding its feature set and its geographic reach, which bodes well for its long-term viability. For the Australian player, this competition is good news. It means more choices, better service, and hopefully, lower fees as the providers fight for your business.
In the end, the choice of a payment method is a personal one, based on your individual priorities. If speed and control are paramount, MiFinity is a strong contender. If you’re willing to sacrifice a bit of speed for potentially lower fees, a bank transfer might be sufficient. If anonymity is your primary concern, you’re looking at a different class of payment methods entirely, with all the risks that entails. The key is to make an informed decision, based on a clear understanding of the costs and benefits. The casino’s marketing will try to sway you with promises of “instant” and “free,” but the reality is always more nuanced. Your job is to see past the hype and make the choice that best serves your financial interests. And that choice, like all choices in gambling, should be made with your eyes wide open.
DV77 Casino Free Spins 2026: A Cynic’s Guide to Spinning Without Losing Your Mind
Does MiFinity have a mobile app for managing casino transactions?
Yes, MiFinity offers a dedicated mobile application for both iOS and Android devices. The app allows you to manage your wallet, make deposits to casinos, and request withdrawals directly from your phone. It includes security features like biometric login (fingerprint or face recognition) and two-factor authentication. The app’s interface is streamlined for mobile use, making it easier to navigate than the desktop site on a small screen. However, the initial account setup and verification process are still often easier to complete on a desktop computer, where uploading documents and entering details is less cumbersome.
What are the daily and monthly limits for MiFinity transactions?
MiFinity imposes its own transaction limits, which are separate from any limits set by the casino. These limits can vary based on your account verification level and your transaction history. Typically, a newly verified account might have a monthly limit of around €2,000-€5,000 for transfers. Higher limits can be requested and may be granted based on your usage and additional verification. It’s crucial to check your specific limits within your MiFinity account dashboard, as exceeding them will result in a failed transaction, regardless of what the casino’s cashier page says.
Can I use MiFinity to claim casino bonuses?
In most cases, yes. Casinos that accept MiFinity for deposits generally allow you to claim their welcome bonuses and other promotions using that method. However, there are occasional exceptions where certain payment methods are excluded from bonus eligibility. This is always stated in the bonus terms and conditions. Before making a deposit with the intent to claim a bonus, verify that MiFinity is not on the exclusion list. It would be a frustrating experience to deposit, only to find out the bonus wasn’t applied because of your chosen payment method.
How does MiFinity compare to cryptocurrency for casino withdrawals?
MiFinity and cryptocurrency serve different player profiles. MiFinity offers stability and regulatory recourse; the value of your withdrawal doesn’t fluctuate, and you have a licensed entity to contact in case of issues. Cryptocurrency offers speed and potentially greater privacy, but with significant volatility and a lack of regulatory protection. A Bitcoin withdrawal might arrive in your wallet in minutes, but its value could drop 5% before you have a chance to convert it to fiat. MiFinity withdrawals are slower (typically 24 hours) but the amount you receive is the amount you requested. The choice depends on whether you prioritize certainty or speed.
独自に開発した
タイピングソフトを販売しております。
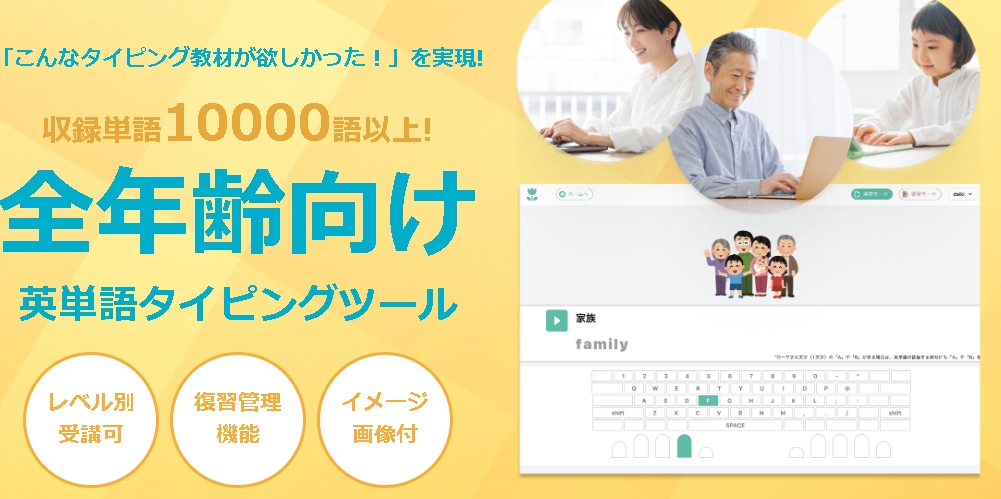
単語学習、聞き取り学習、タイピング練習はもちろん。
できなかった部分だけを重点的に学習できるように復習機能もついています。
また、中1レベルからTOEIC900点クラスまで網羅している為
無料お試し版がご利用いただけますので