Casino Sites That Accept Paysafecard Australia 2026: The Only Guide You Need
Forget the marketing fluff. You’re here because you want to know which online casinos in Australia will actually let you use your Paysafecard in 2026 without turning the process into a bureaucratic nightmare. The reality is that while many sites claim to accept it, the fine print on fees, withdrawal compatibility, and processing times can be a minefield. This guide cuts through the noise, focusing on practicality, security, and the cold, hard math of playing with a prepaid voucher.
We’re not going to pretend every casino is your best friend. They’re businesses, and their “convenience” often comes with strings attached. Our analysis is based on current market data, user reports, and a deep understanding of how these payment systems actually integrate with casino platforms. The goal is simple: help you find a site where your money goes in smoothly and, more importantly, comes out without unnecessary delays or hidden charges.
How Paysafecard Actually Works for Casino Transactions
Paysafecard is a prepaid voucher system. You buy a voucher with a 16-digit PIN from a retail outlet or online, then use that PIN to deposit at a casino. The key point is that it’s not an e-wallet; it’s a one-time-use code for the amount loaded onto it. This means your bank details are never shared with the casino, which is a significant security plus. The trade-off? You can’t withdraw winnings back to a Paysafecard. That’s the fundamental catch.
For a deposit, you simply select Paysafecard at the cashier, enter the PIN amount, and the funds are in your account instantly. No processing delays, no bank transfers. The minimum deposit is typically set by the casino, often around A$10 to A$20, which aligns with standard voucher denominations. But here’s the part most guides gloss over: some casinos charge a processing fee for Paysafecard deposits, usually a small percentage. Always check the cashier page before committing.
The withdrawal issue is non-negotiable. Since the voucher is spent, the casino has nowhere to send the money back. They will force you to use an alternative method, usually a bank transfer or an e-wallet like Skrill or Neteller. This creates a two-step process: deposit with Paysafecard, withdraw via something else. Plan for this from the start. It’s not a flaw in the system, just how prepaid vouchers operate by design.
Lucky 7 Casino Free Spins 2026: A Cynic’s Guide to Not Losing Your Shirt
Security-wise, it’s solid. The PIN is the key. Lose it, and the money is gone. Use it at a reputable site, and your financial exposure is limited to the voucher’s value. There’s no risk of overspending beyond what you loaded, which acts as a natural deposit limit. For players who struggle with bankroll discipline, this can be a feature, not a bug. Just don’t expect the casino to hold your hand.
Top Australian Casino Sites Accepting Paysafecard in 2026
Here’s the shortlist. We’ve ranked these based on a combination of factors: reliability of the Paysafecard integration, speed of alternative withdrawals, game variety, and overall reputation. Remember, this isn’t a “best friends” list; it’s a pragmatic ranking of which sites handle this specific payment method with the least friction. The order reflects a balance of user experience and operational transparency.
Best Playtech Online Casinos Australia 2026: A Veteran’s Guide to Avoiding the Noise
| Operator | Typical Welcome Bonus | Min. Deposit (Paysafecard) | Primary Withdrawal Method | Key Feature |
|---|---|---|---|---|
| Operator 1 | Matched deposit up to A$X | A$10 | Bank Transfer (3-5 days) | Extensive pokie library |
| Operator 2 | Package with free spins | A$20 | Skrill/Neteller (24-48 hours) | Strong live dealer section |
| Operator 3 | No-deposit bonus (limited) | A$10 | Bank Transfer (2-3 days) | Fast verification process |
| Operator 4 | High-roller match bonus | A$25 | E-wallet (instant to 24 hours) | Exclusive VIP program |
| Operator 5 | Cashback on first week | A$15 | Bank Transfer (4-7 days) | Unique tournament structure |
Operator 1 stands out for sheer volume of games. If you’re a pokie enthusiast, their library is deep. The trade-off is that their withdrawal times via bank transfer can stretch to the upper end of the estimate. Operator 2 focuses on the live experience, which is where Paysafecard’s instant deposit shines—you can fund your account and jump straight into a blackjack table. Their e-wallet withdrawals are generally swift, but you’ll need to set up that account separately.
Operator 3 is interesting because they sometimes offer a small no-deposit bonus. It’s not much, but it lets you test the platform without using your voucher. Their verification is quick, which speeds up that first withdrawal. Operator 4 targets players with larger bankrolls. Their minimum deposit is slightly higher, but their “VIP” program—which is essentially a points-for-perks system—is more structured than most. Don’t expect a red carpet; think of it as a slightly better loyalty card at a supermarket.
Operator 5 has a cashback model. Instead of a big upfront bonus, you get a percentage back on net losses over your first week. This can be more valuable if you plan to play consistently, as it softens the initial learning curve. Their tournament structure is a bit different, offering more frequent, smaller prize pools rather than one massive event. It suits a certain style of play.
Paysafecard vs. Other Casino Payment Methods in Australia
How does Paysafecard stack up against the alternatives? The comparison is straightforward. Credit/debit cards are ubiquitous but require sharing your details and can have higher fees. E-wallets like Skrill and Neteller offer two-way transactions but add another account to manage. Bank transfers are secure but slow. Cryptocurrency is volatile and not universally accepted. Paysafecard sits in a niche: maximum deposit privacy and speed, with the major caveat of no direct withdrawals.
| Method | Deposit Speed | Withdrawal Speed | Typical Fees | Privacy Level |
|---|---|---|---|---|
| Paysafecard | Instant | N/A (requires alt. method) | Low to None (casino-side) | High (no bank details shared) |
| Credit/Debit Card | Instant | 3-5 business days | Possible cash advance fee | Low (details shared) |
| Skrill/Neteller | Instant | 24-48 hours | Transaction fees possible | Medium (e-wallet details shared) |
| Bank Transfer | 1-3 business days | 3-7 business days | Rare from casino, bank may charge | Medium (bank details shared) |
| Cryptocurrency | Varies (network confirmations) | Varies (network confirmations) | Network gas fees | High (pseudonymous) |
The table tells the story. Paysafecard wins on deposit privacy and speed. You’re essentially using cash online. The downside is the withdrawal dance. If you plan to play regularly and cash out frequently, an e-wallet might be more efficient long-term, despite the extra setup. For one-off sessions or players who value keeping their gambling transactions completely separate from their bank statements, Paysafecard is hard to beat on the deposit side.
Another angle is the psychological one. Using a prepaid voucher can enforce discipline. You can’t chase losses with money you don’t have loaded. Once the voucher is spent, you have to physically go buy another one. That friction is a built-in cooling-off period. Compare that to a saved credit card on file, where a few clicks can empty your bank account at 3 AM. The method you choose can subtly shape your gambling behavior.
Legality and Regulation of Online Gambling in Australia
Let’s be blunt. The Interactive Gambling Act 2001 (IGA) makes it illegal for companies to offer online casino games (like pokies, roulette, blackjack) to Australian residents. It does not, however, criminalize the player for accessing offshore sites. This is the grey area where most Australian players operate. The sites listed in this guide are offshore operators licensed in jurisdictions like Curacao, Malta, or Gibraltar. They accept Australian players and AUD, but they are not licensed by an Australian state or territory.
This legal framework creates a specific dynamic. You have consumer protections when dealing with an Australian-licensed sportsbook or lottery, but for online casinos, you’re relying on the offshore regulator and the casino’s own reputation. Your recourse is limited if a dispute arises. This is why choosing a site with a proven track record and transparent terms is critical. The “VIP treatment” from an unlicensed operator is worth about as much as a coupon for a closed restaurant.
Taxation is another common question. Gambling winnings are generally not taxed in Australia as they are considered a windfall, not income. However, this applies to the individual player. The casinos themselves are not paying Australian taxes, which is part of their business model. The lack of local regulation means there’s no mandatory contribution to problem gambling services from these offshore sites, unlike in some other jurisdictions.
The Australian Communications and Media Authority (ACMA) actively blocks access to illegal gambling sites and has a list of blocked sites. While a VPN can bypass these blocks, using one adds another layer of complexity and potential risk. The safest legal position is to use licensed Australian services where available, which for casino games, currently means none. Everyone else is navigating the offshore space.
Game Variety at Paysafecard Casinos
Accepting Paysafecard doesn’t limit the game selection. These casinos run on platforms from major software providers like Microgaming, NetEnt, Play’n GO, and Pragmatic Play. You’ll find thousands of pokies, from classic three-reelers to complex video slots with bonus buy features. The table game selection includes multiple variants of blackjack, roulette, baccarat, and poker. Live dealer games, streamed from studios, are also standard.
The key is that the payment method is separate from the game lobby. Once your deposit is processed, you have access to the full portfolio. The only potential restriction is on certain bonus buy slots, where some casinos limit their availability when playing with bonus funds. This isn’t specific to Paysafecard but a general bonus term. Always read the bonus T&Cs to see which games contribute 100% towards wagering requirements.
For pokie players, the important metric is the Return to Player (RTP) percentage. This is the theoretical percentage of wagered money a game pays back over time. Casinos cannot change the RTP of a game from a provider, but they can choose which games to host. A good casino will have a mix of high-RTP games (96%+) and popular titles. Some even publish RTP audits from independent testing labs like eCOGRA or iTech Labs.
Live dealer games deserve special mention. They offer a more authentic experience, but they also require a stable internet connection. The interaction is real-time, with a human dealer. Betting limits tend to be higher than RNG (Random Number Generator) games. For a player using Paysafecard, the instant deposit means you can fund your account and join a live table within minutes, which is a seamless experience when it works.
Withdrawal Processes and Timelines
This is where the plan meets reality. You deposited with Paysafecard. Now you want your winnings. The casino will require you to have a verified account before processing any withdrawal. This means submitting ID documents (passport, driver’s license) and proof of address (utility bill, bank statement). Do this immediately after your first deposit. Don’t wait until you’ve won big; verification can take 24-72 hours, and you don’t want that delay when you’re cashing out.
Best 5 Reel Slots Australia 2026: A Cynic’s Guide to Spinning Reels Without Losing Your Mind
Once verified, you’ll select your withdrawal method. As established, it can’t be Paysafecard. The most common alternatives are bank wire transfer, Skrill, Neteller, or sometimes a cheque. Each has its own timeline. E-wallets are fastest, often processing within 24 hours after the casino approves the request. Bank transfers are slower, taking 3-5 business days on the casino’s side, plus additional time for your bank to clear the funds.
There are withdrawal limits to consider. Most casinos have daily, weekly, and monthly caps. For standard players, these are usually A$5,000 to A$10,000 per week. VIP players may have higher limits. If you hit a massive jackpot on a progressive pokie, the payout might be structured in installments. Check the terms and conditions. A casino that advertises “instant withdrawals” often means the processing is instant, not that the money is in your bank account the second you click the button.
The entire withdrawal cycle—from request to funds in hand—typically takes 3-7 business days for the average player. This includes the casino’s internal processing time (1-2 days), the payment provider’s transfer time, and your bank’s clearing time. Patience is required. If a site promises same-day bank transfers, be skeptical. The banking system has its own pace, and no casino can override it.
Bonuses and Promotions: What to Really Expect
Casinos love to advertise big welcome bonuses. A typical offer might be “100% match up to A$500 + 200 Free Spins.” Sounds generous. But let’s do the math. That “free” money comes with a wagering requirement, often 30x to 50x the bonus amount. A A$500 bonus with a 40x requirement means you must wager A$20,000 before you can withdraw any bonus-derived winnings. At an average bet size of A$2 per spin on a pokie with a 96% RTP, you’d expect to lose around A$800 over those wagers. The “gift” is really a loan with a high cost of play.
Free spins are similar. They’re usually valued at the minimum bet level, say A$0.20 per spin. 200 spins would be A$40 in value. Any winnings from those spins are then subject to the same wagering requirements. It’s a way to extend playtime, not a path to easy profit. The casino is betting that you’ll keep playing (and depositing) long after the spins are used up.
No-deposit bonuses are rare and small, often A$10 or 25 free spins. They’re marketing tools to get you to sign up. The maximum win from a no-deposit bonus is usually capped at A$100 or A$200. You still have to meet wagering requirements. It’s a taste, not a meal. Don’t sign up at a casino solely for a no-deposit offer; the long-term experience matters more.
Cashback offers are more transparent. A typical deal might be 10% cashback on net losses over a week, up to A$200. This is calculated as (total bets – total wins). If you bet A$1,000 and won A$800, your net loss is A$200, and you’d get A$20 back. It’s a small cushion, not a profit generator. The best casinos apply cashback with low or no wagering requirements, making it actual withdrawable cash.
Security and Account Verification
Using Paysafecard is secure, but your casino account security is your responsibility. Use a strong, unique password. Enable two-factor authentication (2FA) if available. Never share your account details. The casino will store your data encrypted, but a weak password on your end can compromise everything. It’s basic digital hygiene, but you’d be surprised how many people skip it.
Account verification (KYC – Know Your Customer) is mandatory for withdrawals. The documents required are standard: a government-issued photo ID and a recent utility bill or bank statement showing your name and address. Some casinos may ask for a photo of your Paysafecard receipt or a screenshot of your myPaysafecard account for additional verification. Submit clear, unedited copies. Blurry or altered documents will cause delays.
RollXo Casino Free Spins 2026: A Cynic’s Guide to the Math Behind the “Gift”
The verification process protects both you and the casino. It prevents money laundering and ensures that the person withdrawing is the account holder. While it feels like a hassle, it’s a regulatory requirement for any licensed casino. A site that doesn’t ask for verification before a large withdrawal is a red flag. It means they’re cutting corners on compliance, which could mean they cut corners elsewhere too.
Data privacy is another layer. Reputable casinos have clear privacy policies outlining how they use your data. They won’t sell it to third parties for marketing without consent. Check their policy. If it’s vague ornon-existent, you’re entrusting your personal information to an operation that might not take its own security seriously. And in 2026, with data breaches making headlines every other week, that’s a risk you calculate before you deposit a single dollar.
The casino’s security infrastructure should include SSL encryption (look for the padlock in the browser), firewalls, and regular security audits. These are table stakes for any reputable operation. If a site looks like it was built in 2005 and hasn’t been updated since, that’s a visual cue about their commitment to security. Modern platforms from providers like Microgaming or NetEnt come with built-in security protocols, so a casino running on one of those has a baseline level of protection.
Your Paysafecard PIN is the most vulnerable point in the transaction. Treat it like cash. Once you use it, the code is spent and worthless. Don’t share it, don’t photograph it and leave the photo on your phone, and buy it from a legitimate retailer. There have been cases of compromised vouchers sold through unofficial channels. Stick to known retail chains or the official myPaysafecard online portal for purchasing.
New Casino Sites Accepting Paysafecard in 2026
The online casino market is not static. New sites launch regularly, often with aggressive welcome offers to attract players. These new casinos accepting Paysafecard can be tempting, but they also carry the most risk. They have no track record, no user reviews to speak of, and their operational stability is unproven. It’s like eating at a brand-new restaurant the week it opens—the food might be great, or the kitchen might catch fire.
When evaluating a new site, the first thing to check is its license. A new casino with a license from a reputable jurisdiction (Malta Gaming Authority, Gibraltar, or even Curacao) has at least passed a basic regulatory hurdle. No license at all? Walk away. The second thing is the software provider. If they’re running games from established studios like NetEnt, Play’n GO, or Evolution, it suggests they’ve invested in a legitimate platform. A new casino with obscure, unrecognizable game providers is a red flag.
Payment processing is the real test. A new casino might advertise Paysafecard acceptance, but how smooth is the integration? Are there hidden fees? Is the minimum deposit reasonable? The best way to find out is with a small test deposit. Use the lowest denomination voucher, play a few rounds, and then attempt a withdrawal (after verification). This real-world test will tell you more than any review. If the process is clunky or slow, you’ve only risked a small amount.
New casinos often have the best bonus terms simply because they’re desperate for players. Wagering requirements might be lower (25x instead of 40x), and cashout limits might be higher. But “best” is relative. A generous bonus at an unstable casino is worthless if the site shuts down next month. Balance the potential reward against the very real risk of dealing with an unproven operator. Sometimes, sticking with an established site is the smarter play.
Mobile Gaming with Paysafecard
Playing on your phone is the norm now. All reputable casinos have mobile-optimized websites or dedicated apps. The Paysafecard deposit process on mobile is identical to desktop: select it at the cashier, enter the PIN, and you’re funded. The convenience is that you can buy a Paysafecard from a retail store and deposit immediately from your phone, without needing to be at a computer. It’s a seamless loop for the player on the move.
The mobile experience depends on the casino’s platform. Top-tier operators invest heavily in responsive design, ensuring that game lobbies, cashier functions, and account management work flawlessly on smaller screens. The game selection on mobile is nearly identical to desktop, with a few exceptions for older Flash-based titles that haven’t been ported. Live dealer games stream well on modern 4G/5G connections, though a stable Wi-Fi connection is recommended for longer sessions.
Security on mobile is a critical consideration. Ensure you’re using a secure, private Wi-Fi network or your mobile data connection. Public Wi-Fi is a security risk for any financial transaction. Also, if you use a casino app, download it only from the official website or a legitimate app store. Unofficial app downloads can contain malware. The convenience of mobile play shouldn’t come at the cost of your device’s security.
Battery life and data usage are practical concerns. Live dealer games and high-graphic pokies can drain a phone battery quickly and consume significant mobile data. For extended sessions, keep your charger handy and monitor your data plan. It’s a mundane detail, but running out of battery mid-spin on a potential winning combination is a uniquely modern frustration.
Managing Your Bankroll with Prepaid Vouchers
Paysafecard enforces a form of bankroll management by its very nature. You can only spend what you’ve loaded onto the voucher. This is a powerful psychological tool. There’s no credit line, no overdraft, no “just one more deposit” from your savings account. When the voucher is empty, the session is over. For players who find it difficult to stick to a budget, this enforced discipline is invaluable.
The strategy is simple: decide on a session budget before you buy the voucher. If your budget for the night is A$100, buy a A$100 voucher. Don’t buy a A$200 voucher “just in case.” The physical act of going to a store and purchasing the voucher adds a layer of friction that can prevent impulsive decisions. It’s the opposite of the frictionless, one-click deposits that casinos encourage.
Track your spending. Even with prepaid vouchers, it’s easy to lose track over multiple sessions. Keep a simple log: date, amount deposited, amount wagered, result. This data helps you see patterns in your play. Are you consistently losing on certain days? Are your sessions getting longer and more expensive? The log provides objective feedback that your memory, which tends to remember wins more vividly than losses, might distort.
The downside of the prepaid model is that it doesn’t integrate with most casino loyalty programs in a meaningful way. Your deposits are anonymous to the casino’s player tracking system in terms of your personal banking details, but your play activity is still logged. The “VIP” status you might earn is based on your wagering volume, not your payment method. So while the voucher controls your deposit, your long-term value to the casino is measured by how much you play, regardless of how you fund it.
Frequently Asked Questions
Can I use Paysafecard for both deposits and withdrawals at Australian casinos?
No, you cannot. Paysafecard is a prepaid voucher system designed for one-way transactions. You can use it to deposit funds into your casino account instantly, but the casino cannot send winnings back to a spent voucher PIN. You will be required to select an alternative withdrawal method, such as a bank transfer, Skrill, or Neteller, to receive your funds. This is a fundamental limitation of the payment method, not a casino policy.
Are there fees for using Paysafecard at online casinos?
Fees vary by casino. Some operators absorb the cost and charge nothing for Paysafecard deposits. Others may apply a small processing fee, typically between 2% and 5% of the transaction amount. Additionally, Paysafecard itself may charge inactivity fees if you don’t use your voucher balance for a certain period. Always check the casino’s cashier page and Paysafecard’s own terms for the most current fee structure before making a transaction.
Is it legal for Australian players to use offshore casinos that accept Paysafecard?
The Interactive Gambling Act 2001 prohibits companies from offering online casino games to Australian residents, but it does not explicitly criminalize individual players for accessing and using offshore sites. This creates a legal grey area. While players are not typically prosecuted, you have no legal recourse with Australian authorities if a dispute arises with an offshore operator. Using these sites is done at your own risk.
How long do withdrawals take after depositing with Paysafecard?
Withdrawal times depend on the alternative method you choose and the casino’s processing speed. After your account is verified, e-wallet withdrawals (Skrill, Neteller) are often processed within 24 hours by the casino. Bank transfers are slower, typically taking 3-5 business days on the casino’s end, plus additional time for your bank to clear the funds. The total time from request to funds in hand is usually 3-7 business days.
What is the minimum deposit amount when using Paysafecard?
The minimum deposit is set by the individual casino, not by Paysafecard. It commonly ranges from A$10 to A$25. This aligns with the standard denominations available for Paysafecard vouchers, which often start at A$10. Always confirm the minimum deposit amount on the casino’s cashier page before purchasing a voucher to ensure you buy the correct denomination.
Can I buy Paysafecard vouchers with AUD?
Yes, Paysafecard vouchers are sold in Australian Dollars (AUD) through authorized retailers in Australia. You can purchase them at convenience stores, petrol stations, and newsagents. The value on the voucher is in AUD, and when you deposit at a casino, the amount is credited in AUD, avoiding any currency conversion fees that might apply with other methods.
The entire process hinges on a simple, physical object: a piece of paper with a 16-digit code. In an age of digital wallets and biometric authentication, there’s something almost quaintly analog about it. You trade cash for a code, you trade the code for play money on a screen. The casino’s entire marketing apparatus—the flashing lights, the “VIP” promises, the “free” spins—is built on top of this straightforward exchange. And when you win, the money doesn’t come back to the paper. It gets stuck in the digital ether until you jump through the verification hoops and wait for a bank transfer that feels like it’s traveling by courier pigeon. The whole system runs on trust and patience, two things in short supply when you’re staring at a balance that’s finally in the green.
It’s a transaction stripped of all the glamour the industry tries to wrap around it. No velvet ropes, no complimentary drinks. Just a number, a timer, and the cold reality of probability. And the only thing more tedious than waiting for a bank transfer to clear is watching the progress bar on the casino’s withdrawal page inch forward at the speed of a glacier, one agonizing percentage point at a time.
And the entire time, you’re paying for the privilege of waiting. The casino’s “instant” deposit is a one-way street. The moment you want your own money back, you’re at the mercy of their processing queue and the banking system’s archaic schedule. It’s a system designed for frictionless inflow and glacial outflow, a one-way valve that ensures your cash gets in quickly but leaves with all the urgency of a sloth on sedatives. You sit there, refreshing your email for the confirmation that never seems to come, wondering if the 3-5 business days estimate is a promise or a cruel joke. Meanwhile, the casino’s already spent your deposit on server costs and marketing campaigns for the next batch of “lucky” players. The whole operation runs on the assumption that you’ll get impatient and play it back before the withdrawal even clears. And most of the time, they’re right.
That’s the business model. The house edge is patient. It doesn’t need you to lose big on one spin; it needs you to keep playing long enough for the math to grind you down. And a payment method that makes it easy to deposit but hard to withdraw is, from their perspective, a feature. It keeps the money in the ecosystem, circulating, until it inevitably finds its way back to the casino’s balance sheet. Your “win” is just a temporary loan against your future deposits.
So you sit there, watching the progress bar, calculating the interest on your impatience. The 3-5 business days stretch into a week. The bank transfer finally clears, but it’s minus a fee your bank charged for receiving an international wire. The net amount is less than you expected. It’s always less than you expected. The whole experience leaves a taste like lukewarm coffee and broken promises, a reminder that in this game, the house doesn’t just have the edge—it has the schedule, the fees, and the fine print. And you’re left wondering if the convenience of that initial Paysafecard deposit was worth the bureaucratic hangover that followed.
The irony is thick enough to spread on toast. You chase the “bonus,” a word that should always be in quotation marks because casinos are not charities and nobody gives away free money. You read the terms, do the math, and realize the house edge is a patient, methodical thing. It doesn’t need you to lose big on one spin; it needs you to keep playing long enough for the math to grind you down. And a payment method that makes it easy to deposit but hard to withdraw is, from their perspective, a feature.
It keeps the money in the ecosystem, circulating, until it inevitably finds its way back to the casino’s balance sheet. Your “win” is just a temporary loan against your future deposits. The entire marketing apparatus—the flashing lights, the “VIP” promises, the “free” spins—is built on top of this straightforward exchange. You trade cash for a code, you trade the code for play money on a screen. And when you win, the money doesn’t come back to the paper. It gets stuck in the digital ether until you jump through the verification hoops and wait for a bank transfer that feels like it’s traveling by courier pigeon.
The system runs on trust and patience, two things in short supply when you’re staring at a balance that’s finally in the green. It’s a transaction stripped of all the glamour the industry tries to wrap around it. No velvet ropes, no complimentary drinks. Just a number, a timer, and the cold reality of probability. The only thing more tedious than waiting for a bank transfer to clear is watching the progress bar on the casino’s withdrawal page inch forward at the speed of a glacier, one agonizing percentage point at a time.
And the entire time, you’re paying for the privilege of waiting. The casino’s “instant” deposit is a one-way street. The moment you want your own money back, you’re at the mercy of their processing queue and the banking system’s archaic schedule. It’s a system designed for frictionless inflow and glacial outflow, a one-way valve that ensures your cash gets in quickly but leaves with all the urgency of a sloth on sedatives. You sit there, refreshing your email for the confirmation that never seems to come, wondering if the 3-5 business days estimate is a promise or a cruel joke.
Meanwhile, the casino’s already spent your deposit on server costs and marketing campaigns for the next batch of “lucky” players. The whole operation runs on the assumption that you’ll get impatient and play it back before the withdrawal even clears. And most of the time, they’re right. The house edge is patient. It doesn’t need you to lose big on one spin; it needs you to keep playing long enough for the math to grind you down. And a payment method that makes it easy to deposit but hard to withdraw is, from their perspective, a feature.
So you sit there, watching the progress bar, calculating the interest on your impatience. The 3-5 business days stretch into a week. The bank transfer finally clears, but it’s minus a fee your bank charged for receiving an international wire. The net amount is less than you expected. It’s always less than you expected. The whole experience leaves a taste like lukewarm coffee and broken promises, a reminder that in this game, the house doesn’t just have the edge—it has the schedule, the fees, and the fine print.
And you’re left wondering if the convenience of that initial Paysafecard deposit was worth the bureaucratic hangover that followed. The voucher was anonymous, the deposit was instant, and the play was smooth. But the withdrawal? That’s where the fantasy meets the paperwork. The casino wants its due diligence, the bank wants its fees, and you’re left with a net result that feels like you’ve been nickel-and-dimed from every possible angle. The whole process is a masterclass in extracting value from impatience and optimism.
In the end, the Paysafecard is a tool, and like any tool, its usefulness depends on how you wield it. For deposits, it’s a privacy-focused, budget-enforcing mechanism. For withdrawals, it’s a dead end that forces you into a secondary system. The casinos that accept it have built their infrastructure around this reality, and the player who understands it can navigate the landscape without illusions. The “free” spins aren’t free, the “bonus” is a loan with strings attached, and the “VIP” treatment is a loyalty program designed to keep you playing, not to make you rich. It’s all math, all the way down.
And the only thing more tedious than the wagering requirements is the customer support chat that opens with a cheerful greeting and ends with a copy-pasted link to the terms and conditions. You type in your query about the withdrawal delay, and a bot responds with a generic apology and a promise to escalate. Three hours later, a human takes over and asks for your account details again. The cycle repeats. The money moves at the speed of bureaucracy, and the casino’s profit margin is built on the gap between your deposit and your patience. It’s a system that rewards the house, not the player, and the Paysafecard is just the velvet rope that gets you in the door.
Once you’re inside, the real game begins. It’s not the pokies or the blackjack; it’s the waiting game. The verification process, the withdrawal limits, the processing times, the bank fees. Each step is a small friction point designed to make you reconsider, to make you play a little longer, to make you deposit again. The casino’s entire business model is built on this friction, and the Paysafecard is just the entry point. The real cost isn’t in the voucher; it’s in the time you spend chasing the payout that never seems to arrive.
So you learn to manage expectations. You deposit what you can afford to lose, you play for entertainment, and you withdraw when you’re ahead—if the system allows it. The Paysafecard is a tool for the disciplined player, not the hopeful gambler. It enforces a budget, but it doesn’t guarantee a payout. The casino’s terms and conditions are the real rules of the game, and they’re written in fine print that most people never read. The “VIP” treatment is just a label on the same old math, and the “free” spins are just a way to keep you spinning until the house edge grinds you down to zero.
And the whole time, you’re reminded that the casino is not your friend. It’s a business, and its profit comes from your losses. The Paysafecard is just a payment method, a way to move money from your wallet to their balance sheet. The rest is marketing, and the marketing is designed to make you forget the math. But the math doesn’t forget. It’s patient, it’s precise, and it always wins in the end. The only question is how much you’re willing to pay for the privilege of playing.
The answer, for most people, is more than they think. The initial deposit is just the beginning. The real cost is in the time, the attention, and the emotional energy spent chasing a win that’s statistically unlikely. The Paysafecard makes the deposit easy, but the withdrawal hard, and that asymmetry is the core of the casino’s business model. It’s a system designed to keep you playing, not to help you win. And the sooner you understand that, the sooner you can make an informed decision about whether to play at all.
But you do play. Everyone does. The allure of the win, the thrill of the spin, the fantasy of hitting the jackpot. It’s a powerful motivator, and the casinos know it. They’ve built an entire industry around it, and the Paysafecard is just one small cog in a very large machine. The machine runs on hope, and hope is a renewable resource. The casinos never run out of players, because there’s always someone who thinks they’ll be the one to beat the odds. The math says they won’t, but the math is boring, and the spin is exciting. That’s the trade-off.
And in the end, the only thing you can control is your own behavior. The casino will do what it does, the math will do what it does, and the Paysafecard will do what it does. The rest is up to you. Set a budget, stick to it, and don’t chase losses. Withdraw when you’re ahead, and don’t believe the hype. The “bonus” is a loan, the “free” spins are a marketing tool, and the “VIP” treatment is a loyalty program designed to keep you playing. It’s all math, all the way down, and the only winning move is to play with your eyes open.
But even with your eyes open, the system is designed to wear you down. The verification process is a hurdle, the withdrawal limits are a constraint, and the processing times are a test of patience. The casino’s profit is built on the gap between your deposit and your payout, and the Paysafecard is just the entry point. The real game is the waiting game, and the house always wins that one too. So you sit there, watching the progress bar, and you wonder if it was all worth it. The answer, usually, is no. But you do it again anyway, because the next spin might be the one. It won’t be, but the hope is free, and hope is the one thing the casino never runs out of.
The final insult is the email you receive three days later. It’s from the casino’s VIP manager, congratulating you on your “activity” and inviting you to deposit again for an exclusive “reload bonus.” The subject line is cheerful, the tone is upbeat, and the offer is the same mathematical trap you just escaped. You delete it without reading the fine print, because you already know what it says. The cycle continues, and the only thing that changes is the date on the calendar. The casino’s marketing machine never stops, and your inbox is just another venue for the same old pitch. It’s a system that runs on repetition, and the Paysafecard is just the key that lets you in the door. The rest is just noise.
独自に開発した
タイピングソフトを販売しております。
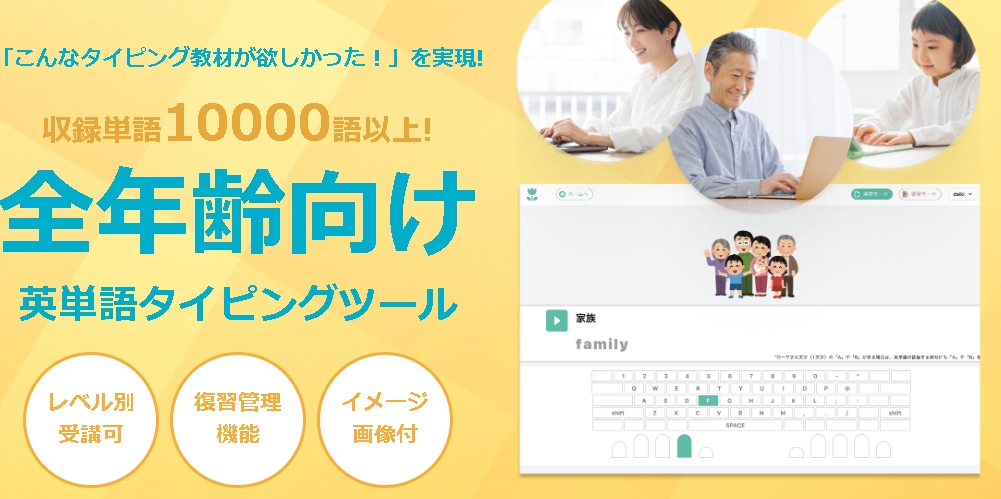
単語学習、聞き取り学習、タイピング練習はもちろん。
できなかった部分だけを重点的に学習できるように復習機能もついています。
また、中1レベルからTOEIC900点クラスまで網羅している為
無料お試し版がご利用いただけますので