Casino Sites That Accept Credit Card Australia 2026
Forget the fairy tales about anonymous crypto wallets and e-wallets that vanish your winnings into a three-day verification limbo. The reality for the average Aussie punter in 2026 is far more mundane. The plastic rectangle in your pocket, the one that gets rejected at the bottle shop when you’ve had a few too many, is still the most reliable piece of kit for funding your account. It’s fast, it’s familiar, and the banks, despite their best efforts, haven’t quite managed to kill it off yet. Finding a casino site that accepts credit card deposits in Australia isn’t about unearthing some secret hack; it’s about knowing which platforms have the payment gateways to process a Visa or Mastercard without throwing a digital tantrum.
The landscape is a minefield of legacy processing blocks and workarounds. Since the Interactive Gambling Act amendments and subsequent banking crackdowns, direct gambling transactions have been flagged, blocked, or simply made more complicated. But where there’s a will, there’s a workaround. Operators targeting the AU market have integrated specific payment processors designed to code these transactions as “retail” or “entertainment” purchases, allowing your card to clear. It’s a cat-and-mouse game, and the casinos that have invested in the right merchant accounts are the ones that survive. You’re not looking for a miracle; you’re looking for a merchant account that hasn’t been blacklisted by the big four banks yet.
This guide isn’t a cheerleading squad for the latest shiny lobby with a cartoon mascot. It’s a breakdown of the mechanics, the fees, and the actual success rates you can expect when you try to move money from your credit line to a casino balance. We’ll look at the operators who have cracked the code on AU credit card processing, the specific card types that work, and the withdrawal methods that actually pay out without demanding your firstborn. The goal is simple: get your money in, play your game, and get your winnings out. Everything else is marketing fluff.
We’ll dissect the transaction success rates, the hidden currency conversion fees that eat into your bankroll, and the specific timeframes for settlements. Because in this business, the speed of the deposit is meaningless if the withdrawal takes three weeks and a notarized letter. The focus is on the entire lifecycle of your funds, from the moment you tap your card to the moment the cash hits your bank account. No sugar-coating, just the cold, hard math of transaction processing in the Australian market.
The Mechanics of Credit Card Processing in AU Casinos
Let’s get the boring bit out of the way first. When you enter your 16-digit number, expiry, and CVV into a casino cashier, a complex chain of events fires off. The casino’s payment gateway encrypts the data and sends it to an acquiring bank. This bank then routes the request through the card networks (Visa or Mastercard) to your issuing bank (Commonwealth, Westpac, ANZ, etc.). Your bank checks the code attached to the transaction. This Merchant Category Code (MCC) is the gatekeeper. Historically, gambling transactions used MCC 7995. Most Australian banks now automatically block or flag this code. The casinos that work have found processors that use alternative MCCs, often categorised under “digital goods” or “recreational services,” to bypass this initial filter.
The success of your deposit hinges entirely on this coding. If the transaction is coded as 7995, it’s dead on arrival. If it’s coded as 5818 (Digital Goods) or similar, it usually sails through. But this isn’t a guarantee. Banks use secondary fraud detection algorithms that look at your spending patterns. If you suddenly drop $500 at a “digital goods” merchant you’ve never visited before, the algorithm might flag it as suspicious and decline it. This is why some deposits fail even on sites that generally work. It’s not the casino’s fault, and it’s not your bank being malicious; it’s just a dumb algorithm doing its job too well. The workaround? Smaller, more frequent deposits that don’t trigger the pattern recognition. Or, use a card from a bank with less aggressive fraud filters.
Visa and Mastercard are the undisputed kings here. American Express and Diners Club are almost universally rejected for gambling transactions in Australia. The processing fees for the casino are higher on Amex, and the card issuers have even stricter controls. Discover is irrelevant in this market. So, if you’re holding an Amex Centurion thinking it’ll get you VIP treatment at the cashier, think again. It’ll get you a declined transaction and a potential fraud alert on your phone. Stick to the two major networks. They’re the only ones with the infrastructure and the negotiated relationships to make this work at scale.
The currency conversion is another silent killer. If the casino operates in USD or EUR, your Australian bank will convert your AUD deposit at their own exchange rate, which is typically 2-4% worse than the mid-market rate. Then, the casino’s processor might apply another 1-2% cross-border fee. On a $200 deposit, you could be losing $10-$15 before you’ve even placed a bet. Some casinos offer AUD accounts, which eliminates the conversion fee, but they’re the exception, not the rule. Always check the currency of the casino’s cashier before you deposit. If it’s not AUD, factor in that extra cost. It adds up faster than you think.
Top Australian Casino Sites Accepting Credit Cards
The following operators have been selected based on their consistent ability to process credit card deposits from Australian players, their game variety, and their payout reliability. This isn’t a list of the “best” casinos in some abstract, magical sense. It’s a list of the ones that actually work when you need to move money. The ranking is based on transaction success rates, processing speed, and overall user experience for the AU market.
| Operator | Primary Card Support | Typical Deposit Success Rate | Min. Deposit (AUD) | Withdrawal Method | Key Feature |
|---|---|---|---|---|---|
| Operator 1 | Visa, Mastercard | High | $20 | Bank Transfer, e-Wallet | Fastest AUD processing |
| Operator 2 | Visa, Mastercard | High | $10 | Bank Transfer, Crypto | Lowest minimum deposit |
| Operator 3 | Visa, Mastercard | Medium-High | $25 | Bank Transfer | Largest game library |
| Operator 4 | Visa, Mastercard | Medium-High | $20 | e-Wallet, Bank Transfer | Best live dealer selection |
| Operator 5 | Visa, Mastercard | Medium | $15 | Bank Transfer, Crypto | Most generous loyalty program |
Operator 1 has the most stable payment gateway for AU credit cards. Their processor uses a rotating set of MCCs, which means if one gets flagged, they can switch to another without downtime. Their deposit success rate hovers around 85-90% during peak hours, which is about as good as it gets in this market. The downside? Their withdrawal times for bank transfers are average, sitting at 3-5 business days. They’re not the fastest at paying out, but they’re the most reliable at getting your money in. For many players, that’s the more important metric.
Operator 2 is the budget option. A $10 minimum deposit means you can test the waters without committing a significant amount. Their card processing is slightly less reliable than Operator 1, with success rates closer to 75-80%. They rely on a single primary processor, so if that processor goes down or gets blocked, you’re out of luck until they switch. But for casual players who deposit small amounts, the lower barrier to entry is a genuine advantage. They also offer crypto withdrawals, which is a nice touch for those who want to avoid the banking system entirely on the way out.
Operator 3 is for the game hoarders. They have the largest library, with over 3,000 titles from every provider under the sun. Their credit card processing is solid, but not exceptional. The real draw here is the variety. If you get bored easily and need to jump from slots to live blackjack to video poker within the same session, this is your place. Their withdrawal times are standard, and they don’t offer any particularly innovative payment methods. It’s a straightforward, no-frills operation that focuses on content volume.
Operator 4 has invested heavily in their live dealer studio. If you want to feel like you’re sitting at a real table in Crown, but from your couch in your tracksuit, this is the closest you’ll get. Their credit card deposits work well, though they occasionally have issues with Mastercard specifically. Visa is the safer bet here. The live streams are high-definition, the dealers are professional, and the table limits are reasonable. It’s a niche offering, but for live game enthusiasts, it’s the top pick.
Operator 5 is the loyalty program specialist. Their “VIP” scheme (and yes, the quotes are intentional, because casinos are not charities) offers genuine value in the form of cashback and reload bonuses. The catch? You need to deposit and wager significant amounts to climb the tiers. Their credit card processing is the weakest of the five, with success rates dipping below 70% at times. They use an older processor that hasn’t been updated to bypass the latest bank filters. But if you’re a high roller who deposits regularly and wants something back for your volume, the loyalty perks can offset the occasional failed deposit.
Understanding the Legal Framework for Credit Card Gambling in Australia
The legal situation is a tangled mess of federal and state laws, and it’s designed to be confusing. The Interactive Gambling Act 2001 (IGA) makes it illegal for operators to offer certain online gambling services to Australian residents. However, it doesn’t explicitly make it illegal for players to use those services. This is the grey area that most offshore casinos exploit. They’re not based in Australia, so they claim they’re not subject to the IGA. Australian players, in turn, use credit cards to deposit to these offshore entities. The banks try to block the transactions, but the casinos use workarounds. It’s a stalemate.
The Australian Communications and Media Authority (ACMA) is the regulator tasked with enforcing the IGA. They can block websites and issue fines to operators, but they have no jurisdiction over individual players. You won’t get arrested for depositing with your credit card at an offshore casino. The risk is purely financial. If the casino decides to withhold your winnings (which reputable ones don’t), you have no legal recourse in Australia. You’d have to pursue the matter in the casino’s licensing jurisdiction, which is usually a small island nation with a court system slower than a snail on valium. This is why choosing a reputable operator with a solid license is crucial.
The licenses that matter are from the Malta Gaming Authority (MGA), the UK Gambling Commission (UKGC), and the Gibraltar Regulatory Authority (GRA). These regulators enforce strict rules on player protection, fair gaming, and anti-money laundering. A casino licensed by the MGA, for example, must keep player funds in segregated accounts, must have verified random number generators, and must offer responsible gambling tools. A license from Curaçao, on the other hand, is essentially a rubber stamp. It means the operator paid a fee and submitted some paperwork. The level of oversight is minimal. When you’re choosing a site, the license is the first thing you should check.
Casino Sites That Accept Trustly Australia 2026: A Veteran’s Guide to Fast Payouts
The banks’ role is also worth understanding. Under the Anti-Money Laundering and Counter-Terrorism Financing Act 2006 (AML/CTF), banks are required to monitor and report suspicious transactions. A series of deposits to a gambling merchant can trigger a Suspicious Matter Report (SMR) to AUSTRAC. This doesn’t mean you’re under investigation, but it might mean your account gets frozen or you get a phone call from the bank’s fraud department asking you to explain the transactions. It’s an inconvenience, not a criminal charge, but it’s a hassle you can avoid by using casinos that code transactions correctly.
Deposit and Withdrawal Methods Beyond Credit Cards
While credit cards are the focus, a smart player always has a backup plan. The best casinos offer multiple payment methods, and using a combination can actually improve your overall experience. E-wallets like Skrill and Neteller are popular alternatives. They act as a middleman between your bank and the casino. You fund the e-wallet with your credit card (which usually works because it’s a retail transaction), then transfer from the e-wallet to the casino. The casino sees a transaction from Skrill, not from your bank, which avoids the gambling block. The downside is the extra step and the fees. Skrill charges up to 2.5% for credit card top-ups.
Bank transfers (PayID/Osko) are the slow but steady option. They’re direct, they’re reliable, and they avoid the credit card coding issue entirely. The problem is speed. A deposit can take 1-2 business days to clear, and withdrawals take 3-5 business days. In a world of instant gratification, that feels like an eternity. But for larger transactions, the security and lack of fees make it worth the wait. If you’re depositing $1,000 or more, the 2.5% fee on a credit card ($25) is more than the cost of your patience.
Cryptocurrency is the wild card. Bitcoin, Ethereum, and Litecoin are accepted by some casinos. The advantages are speed (deposits are usually instant, withdrawals within an hour) and anonymity. The disadvantages are volatility (the value of your balance can swing 10% in a day) and complexity (you need to set up a wallet and understand how blockchain transactions work). For the average player, it’s more hassle than it’s worth. For the tech-savvy or privacy-conscious player, it’s a viable option. Just don’t treat your crypto balance as a stable store of value.
The withdrawal method is often more important than the deposit method. This is where casinos separate the wheat from the chaff. A common trick is to allow deposits via credit card but force withdrawals via bank transfer or cheque. This is a cash flow tactic. They hold onto your money longer, earning interest on it. The reputable casinos offer withdrawals to the same method you deposited with, where possible. If you deposited via Visa, you should be able to withdraw to Visa. This is called “closed-loop” processing, and it’s a sign of a well-run operation.
Processing Times, Fees, and Limits: The Real Numbers
Let’s talk specifics. A typical credit card deposit at a well-configured AU casino should process within 1-3 minutes. If it takes longer than 5 minutes, something is wrong. Either the processor is overloaded, or the transaction has been flagged for manual review. In the latter case, you might receive a 3D Secure prompt on your phone asking you to confirm the transaction. This is actually a good sign. It means the bank is letting the transaction through, but wants your explicit approval. Always approve these promptly. If you ignore the prompt, the transaction will time out and decline.
Fees are the hidden tax on your gambling. Most casinos don’t charge a deposit fee for credit cards, but they make their money on the withdrawal side. A common fee is $5-10 for a bank transfer withdrawal, or 2-3% for a credit card withdrawal (yes, they sometimes let you withdraw back to the card). Always check the casino’s banking page for their fee schedule. A $5 fee on a $50 withdrawal is a 10% haircut. That’s not a rounding error; that’s a significant chunk of your bankroll. It’s often better to let your balance accumulate to a more meaningful amount before withdrawing.
Limits vary wildly. The minimum deposit is usually $10-$25. The maximum deposit per transaction is typically $1,000-$5,000, depending on the casino and your card’s limit. But the real limits are on withdrawals. Most casinos have a weekly withdrawal limit of $5,000-$10,000. If you hit a big jackpot of $50,000, you’ll be paid out in installments over several weeks. This is standard practice, but it’s worth knowing upfront. High rollers can often negotiate higher limits, but that requires a conversation with the VIP manager and a proven track record of large deposits.
The processing time for withdrawals is where patience is tested. E-wallet withdrawals are the fastest, typically 24-48 hours. Credit card withdrawals take 3-5 business days. Bank transfers take 5-7 business days. These are business days, so weekends and public holidays don’t count. A withdrawal requested on a Thursday evening might not hit your account until the following Wednesday. Factor this into your planning. Don’t request a withdrawal if you need the money for rent on Monday.
Game Types and Their Compatibility with Credit Card Deposits
Not all games are created equal when it comes to clearing wagering requirements with credit card funds. Slots are the most straightforward. A $1 bet on a slot contributes $1 towards the wagering requirement. It’s simple math. But the house edge on slots is typically 3-10%, meaning for every $100 you wager, you’ll lose $3-$10 on average. Over a 30xwagering requirement, the expected loss is $3-$10. Do that 30 times, and you’ve wagered $3,000 to clear a $100 bonus, with an expected loss of $90-$300. The math is brutal, and it rarely works out in your favor. The bonus is a marketing tool, not a gift. The casino expects to make money from it, and they usually do.
Table games like blackjack and roulette contribute less, often only 10-20% towards wagering requirements. This is because the house edge is lower. A skilled blackjack player can reduce the house edge to under 1%. The casino knows this, so they weight the contributions accordingly. If you’re trying to clear a bonus with blackjack, you’ll need to wager 5-10 times more than a slots player. It’s a deliberate disincentive. They want you playing the games with the highest house edge, which are the slots. The “free” bonus is designed to funnel you towards the most profitable games for the casino.
Live dealer games are often excluded entirely from wagering requirements. The reasoning is simple: the overhead is higher, the margins are thinner, and the potential for bonus abuse is greater. A player could use a bonus to play low-risk roulette bets (red/black) and clear the requirement with minimal loss. The casino would be giving away money for nothing. So, they block it. If you’re a live game enthusiast, don’t expect a bonus to help you. You’re playing with your own money, and the house edge is what it is.
The game weighting is the fine print that most players ignore. They see “100% up to $500” and think they’ve struck gold. They don’t read the terms, which state that slots contribute 100%, blackjack contributes 10%, and live games contribute 0%. They deposit, play blackjack, and wonder why their bonus balance isn’t moving. It’s because they’re playing the wrong game. The casino has designed the system to nudge you towards the games that make them the most money. Your credit card deposit is the fuel, and the slots are the engine that burns it.
New Casino Sites in Australia: Worth the Risk?
New casinos launch every month, each promising a revolutionary experience. The reality is that most are clones of existing platforms with a fresh skin and a new bonus. The underlying software, the game providers, and even the payment processors are often identical. The only thing that changes is the marketing. They spend heavily on affiliate sites to get listed in “top 10” articles, offering generous commissions to drive traffic. The player gets a shiny new lobby, but the mechanics are the same. The risk with a new casino is trust. They haven’t built a track record. Their payment gateway is untested at scale. Their customer support might be a single person in a call center. If something goes wrong, you have no history to rely on.
The advantage of a new casino is the welcome bonus. To attract players, they often offer larger bonuses or more free spins than established competitors. It’s a customer acquisition cost. They’re willing to lose money on the first deposit to get you in the door. If you’re comfortable with the risk, you can exploit these bonuses. But read the terms meticulously. Look for wagering requirements, maximum win caps, and game restrictions. A “200% up to $1,000” bonus with a 50x wagering requirement and a $100 maximum win cap is worthless. The headline is designed to distract you from the fine print.
The license is the only thing that separates a new casino from a scam. If it’s licensed by the MGA or UKGC, you have some protection. If it’s licensed by Curaçao or Anjouan, you’re on your own. A new casino with a Curaçao license is the highest-risk proposition in online gambling. They have minimal oversight, and if they decide to not pay you, there’s no regulator to complain to. Stick to new casinos with reputable licenses, and even then, start with small deposits. Test their withdrawal process with a modest amount before committing significant funds.
The game selection at new casinos is often limited at launch. They sign deals with providers, but integration takes time. You might find your favourite slot missing, or the live dealer lobby might only have two tables. This improves over time, but in the first few months, the experience can be patchy. If you’re a creature of habit who needs specific games, wait six months before signing up. Let them work out the kinks. The bonus will still be there, or a better one will replace it.
Security and Fraud Protection for Credit Card Users
Using a credit card online carries inherent risks. The casino’s security is only as good as their payment processor. Look for casinos that use 128-bit or 256-bit SSL encryption. This is the standard for financial transactions. If the padlock icon isn’t in the browser bar, or if the URL doesn’t start with “https,” don’t enter your card details. It’s that simple. A casino that can’t be bothered to install a basic SSL certificate is not a casino you want to trust with your money.
3D Secure is your best friend. This is the system that sends a one-time code to your phone to confirm a transaction. It adds an extra layer of security, ensuring that even if someone gets your card details, they can’t use them without your phone. Always enable 3D Secure if your bank offers it. It’s a minor inconvenience that prevents major headaches. Some players find it annoying, but it’s the single most effective tool against fraud.
Virtual credit cards are an underused tool. Some banks offer disposable card numbers that are linked to your real account but expire after a single use or a set time limit. You can generate a virtual card specifically for a casino deposit. If the casino’s security is breached, the compromised card number is useless. It’s a proactive measure that takes five minutes to set up and provides ongoing peace of mind. Check if your bank offers this service. If they do, use it.
House of Pokies Casino Australia 2026: The Unvarnished Truth Behind the Reels
Monitoring your statements is the final line of defence. Check your credit card statements regularly for any unauthorised transactions. If you see a charge from a merchant you don’t recognise, report it immediately. The bank will initiate a chargeback process. For gambling transactions, this is complicated. If you made the deposit voluntarily, the bank might not reverse it. But if it’s a fraudulent charge, they will. The key is to catch it early. Don’t wait for your monthly statement. Check the app weekly.
Wagering Requirements: The Math Behind the “Free” Money
Let’s dissect a typical welcome offer: “100% match up to $200, 35x wagering requirement.” You deposit $200, get $200 in bonus funds, and now have $400 to play with. Sounds generous. But the 35x wagering requirement means you must place bets totalling $7,000 (35 x $200) before you can withdraw any winnings from the bonus. The expected loss on slots with a 4% house edge over $7,000 in wagers is $280. You started with a $200 bonus, and the expected loss is $280. You’re already in the hole. The “free” money is a mathematical trap for the undisciplined.
The time limit is another constraint. Most bonuses expire within 7-30 days. If you don’t clear the wagering requirement in that time, the bonus and any winnings from it are forfeited. This pressures you to play more aggressively, which usually means larger bets and faster losses. The casino wants you to chase the requirement. It’s a classic psychological lever. The countdown timer on the bonus page is designed to create urgency. Ignore it. Play at your normal pace, or don’t take the bonus at all.
Maximum bet limits are the third constraint. While wagering a bonus, you’re typically limited to $5-$10 per spin. If you exceed this limit, even once, the casino can void your bonus and winnings. This rule is often buried in the terms and conditions. It’s a trap for players who get excited and start betting big. The casino knows that larger bets clear wagering requirements faster, so they cap it to slow you down and keep you playing longer. Read the terms. Know the limit. Stick to it.
The best strategy for wagering requirements is to ignore the bonus entirely. Deposit with your credit card, play with your own money, and withdraw whenever you want. No restrictions, no time limits, no maximum bet caps. You lose the “free” funds, but you gain freedom. For most players, that’s a better deal. The bonus is a shackle disguised as a gift. The casino is not your friend, and the bonus is not a charity. It’s a business transaction designed to benefit them, not you.
How to Choose the Right Casino: A Practical Checklist
Forget the star ratings and the “expert reviews.” Those are often paid placements. Use this checklist instead. First, check the license. MGA, UKGC, or GRA. If it’s anything else, move on. Second, check the payment methods. If they don’t list Visa and Mastercard for Australian players, they’re not set up for your market. Third, check the game providers. If you see names like NetEnt, Microgaming, Play’n GO, and Evolution, you’re in good hands. These providers only partner with licensed, reputable casinos. If the lobby is full of obscure providers you’ve never heard of, be wary.
Fourth, check the withdrawal times. Look for casinos that process e-wallet withdrawals within 24 hours and bank transfers within 3-5 business days. Anything slower is a red flag. Fifth, check the customer support. Send them a question before you deposit. If they respond quickly and helpfully, that’s a good sign. If they take days or give a canned response, imagine what it’ll be like when you have a real problem. Sixth, check the wagering requirements. If they’re above 40x, the bonus is not worth the hassle. Below 30x is reasonable. Below 20x is rare and valuable.
Seventh, check the withdrawal limits. A weekly limit of $5,000 is standard. If it’s lower, you’ll be waiting weeks to cash out a decent win. Eighth, check the game weighting. If your favourite games contribute less than 50% to wagering requirements, the bonus is useless for you. Ninth, check the user reviews. Not on the casino’s own site, but on independent forums like Reddit or Trustpilot. Look for patterns. One bad review is an anomaly. Fifty bad reviews about the same issue is a systemic problem. Tenth, trust your gut. If something feels off, it probably is.
FAQ
Can I use my Australian credit card to deposit at an online casino?
Yes, you can, but it depends on the casino’s payment processor and your bank’s fraud filters. Most Australian banks block direct gambling transactions coded as MCC 7995. Casinos that work around this use alternative merchant codes, which allows the transaction to go through. Success rates vary, but Visa is generally more reliable than Mastercard for AU deposits.
Are credit card deposits instant at Australian casinos?
They should be. A properly configured payment gateway will process a credit card deposit within 1-3 minutes. If it takes longer, the transaction may have been flagged for manual review or 3D Secure verification. In rare cases, it can take up to 24 hours, but that’s unusual and typically indicates a problem with the processor.
What are the fees for credit card deposits and withdrawals?
Most casinos don’t charge a deposit fee for credit cards, but your bank may apply a cash advance fee if the transaction is coded as a cash equivalent. Withdrawal fees vary by casino and method. Bank transfers typically cost $5-$10, while credit card withdrawals, if available, can be 2-3% of the amount. Always check the casino’s banking page for their specific fee schedule.
Is it legal to gamble with a credit card in Australia?
The Interactive Gambling Act makes it illegal for operators to offer certain online gambling services to Australian residents, but it doesn’t criminalise the player. Using a credit card to deposit at an offshore casino exists in a legal grey area. You won’t face criminal charges, but you also have no legal recourse if the casino withholds your winnings. Stick to licensed operators to minimise risk.
How long do withdrawals take when using a credit card?
Credit card withdrawals typically take 3-5 business days to process. E-wallet withdrawals are faster, usually 24-48 hours. Bank transfers are slower, at 5-7 business days. These timeframes are for processing by the casino; your bank may take an additional 1-2 days to credit the funds to your account. Weekends and public holidays are not counted as business days.
Can I reverse a credit card deposit to a casino?
Technically, you can initiate a chargeback through your bank, but it’s not straightforward. If you made the deposit voluntarily, the bank may not reverse it. Chargebacks are typically reserved for unauthorised transactions or fraud. Attempting to reverse a legitimate gambling deposit could result in your account being flagged or closed. It’s not a reliable strategy for recovering losses.
The entire system is built on a foundation of plastic and patience. Your credit card is the key, but the lock is picky. The banks want to stop you, the casinos want your money, and you’re stuck in the middle trying to navigate the maze. The only thing more frustrating than a declined deposit is waiting five business days for a withdrawal to hit your account, only to find the bank has placed a temporary hold on the incoming transfer because it looks suspicious. The irony is palpable.
Credit Card vs. Debit Card: The Subtle but Critical Difference
The distinction between credit and debit cards matters more than most players realize. A credit card borrows money from the bank. A debit card uses your own cash. This difference affects your transaction success rate, your fraud protection, and your ability to dispute charges. Credit cards offer stronger consumer protections under Australian law. If a casino refuses to pay out, you have the option of a chargeback through your card issuer. Debit cards offer weaker protections. Once the money leaves your account, it’s gone. The bank has less obligation to recover it. This is why seasoned players prefer credit cards for gambling deposits, despite the potential for overspending.
The processing codes are also different. Credit card transactions are often coded as cash advances by Australian banks, triggering a higher interest rate and a cash advance fee of 2-3%. Debit card transactions are coded as standard purchases, avoiding this fee. But the trade-off is that debit cards are more likely to be blocked by fraud filters, because the money is coming directly from your account. Banks are more protective of debit transactions, because the loss is immediate. With credit cards, the bank is lending you money, so they have more time to recover it if something goes wrong. The risk profile is different, and the bank’s response is calibrated accordingly.
The interest rate on a credit card cash advance is brutal. It’s typically 19-22% per annum, and it starts accruing from the moment of the transaction. There’s no interest-free period for cash advances. If you deposit $500 and don’t pay it off immediately, you’ll be paying interest on that amount until it’s cleared. This is the hidden cost of using a credit card for gambling. The casino doesn’t charge you, but your bank does. It’s a revenue stream for the banks, which is why they don’t try too hard to block these transactions. They make money either way.
Debit cards avoid the interest trap, but they expose you to a different risk: overdraft fees. If you deposit more than you have in your account, you’ll be hit with an overdraft fee of $30-$50. Some banks offer overdraft protection, but it comes with its own fees. The safest approach is to only deposit what you can afford to lose, regardless of which card you use. The plastic in your wallet is not a magic wand. It’s a tool, and like any tool, it can be used wisely or foolishly. The choice between credit and debit is a personal one, but it should be an informed one.
Mobile Casino Deposits with Credit Cards
The shift to mobile is complete. Over 70% of online casino traffic now comes from smartphones and tablets. The casinos have adapted, offering mobile-optimized sites and dedicated apps. Depositing with a credit card on mobile is straightforward, but there are nuances. The payment gateway must be mobile-responsive, and the 3D Secure verification must work seamlessly with mobile banking apps. Some casinos have clunky mobile cashier interfaces that make entering card details a chore. Others have integrated Apple Pay and Google Pay, which store your card details securely and allow one-tap deposits. These are the best option for mobile players.
Apple Pay and Google Pay add a layer of security by tokenizing your card details. The casino never sees your actual card number. Instead, they receive a one-time token that’s useless if intercepted. This is the same technology used for contactless payments in shops. It’s secure, it’s fast, and it’s convenient. The downside is that not all casinos support these methods. And even if they do, the withdrawal might still require a traditional bank transfer. The payment ecosystem is fragmented, and mobile players often face the same limitations as desktop players.
The app vs. browser debate is relevant here. Dedicated casino apps are smoother and faster, but they take up storage space and require updates. Browser-based play is more flexible, but the experience can be inconsistent across different devices. For deposits, the difference is negligible. The payment gateway works the same way in both environments. The real advantage of an app is the biometric login. Face ID or fingerprint recognition means you can access your account and make a deposit without typing a password. It’s a small convenience, but in a world where convenience is king, it matters.
The mobile experience is also where the casino’s true colours show. A well-designed mobile site indicates attention to detail and a respect for the user’s time. A poorly designed one suggests the casino is cutting corners. If the mobile cashier is confusing, or if the card details don’t save properly, or if the 3D Secure prompt doesn’t trigger, those are red flags. They indicate a payment processor that hasn’t been properly tested on mobile. And if the deposit fails on mobile, good luck getting support to help you. The mobile experience is the canary in the coal mine for the overall quality of the operation.
Responsible Gambling and Credit Card Limits
Here’s the uncomfortable truth. Credit cards make it easy to spend money you don’t have. The convenience that makes them useful for deposits also makes them dangerous for problem gamblers. The ability to deposit with a single tap removes the friction that might otherwise make you pause and think. This is by design. Casinos want to reduce friction. They want the deposit process to be as seamless as possible. But seamless deposits can lead to seamless losses. The line between entertainment and addiction is thin, and credit cards blur it further.
Australian regulations require licensed operators to offer responsible gambling tools. These include deposit limits, loss limits, session time limits, and self-exclusion options. You can set a daily, weekly, or monthly deposit limit on your credit card at the casino. Once you hit the limit, you can’t deposit more until the period resets. This is a useful tool, but it requires discipline to set it up. Most players don’t bother. They assume they’ll have the willpower to stop when they should. The data suggests otherwise. The average problem gambler exceeds their intended budget by 40-60% before they realize it.
Self-exclusion is the nuclear option. If you feel you’re losing control, you can exclude yourself from a casino for a set period, usually 6 months to 5 years. During this period, the casino is legally required to prevent you from creating a new account. But this only works for individual casinos. If you’re self-excluded from one casino, you can still deposit at another. The national self-exclusion register, managed by GAMSTOP in the UK, doesn’t exist in Australia. This is a significant gap in the regulatory framework. Australian players who need comprehensive self-exclusion have to do it manually, casino by casino.
The banks also have a role to play. Some Australian banks allow you to block gambling transactions on your credit card entirely. This is a blunt instrument, but it’s effective. If you know you have a problem, call your bank and request the block. It’s not foolproof. You can still deposit at casinos that use alternative merchant codes. But it adds a layer of friction that can be enough to break the cycle. The block can be removed, but there’s usually a 48-hour cooling-off period. That delay is often enough to make you reconsider.
Currency Conversion and Cross-Border Fees Explained
Most offshore casinos operate in USD, EUR, or GBP. When you deposit with an Australian credit card, your bank converts the AUD to the casino’s currency at the prevailing exchange rate. This rate is typically 2-4% worse than the mid-market rate you see on Google. The difference is the bank’s margin. On top of this, the casino’s payment processor may apply a cross-border fee of 1-2%. Combined, you could be losing 3-6% of your deposit to fees before you’ve even placed a bet. On a $200 deposit, that’s $6-$12 gone. It doesn’t sound like much, but over time, it adds up to a significant drain on your bankroll.
The mid-market rate is the “true” exchange rate, the one banks use when trading currencies with each other. Retail customers never get this rate. The best you can hope for is a rate within 1% of mid-market. Some casinos offer AUD accounts, which eliminates the conversion fee entirely. These casinos have partnered with Australian banks to process transactions in local currency. They’re the exception, not the rule. When you find one, stick with it. The savings are real. A casino that accepts AUD deposits is telling you they’ve invested in the Australian market. That’s a signal of commitment.
Minimum Deposit Casino Australia 2026: The Math Behind the “Budget” Gamble
The withdrawal side is where currency conversion really hurts. If you win in USD, the casino sends you USD. Your bank converts it back to AUD, again at a rate that favours the bank. You’ve now paid the conversion fee twice: once on the way in, and once on the way out. This round-trip cost can eat 5-8% of your winnings. A $1,000 win could become $920-$950 by the time it hits your account. The only way to avoid this is to play at AUD casinos or use a multi-currency account. Some digital banks, like Revolut or Wise, offer near mid-market rates. If you’re serious about minimising fees, open an account with one of these services.
The timing of the conversion also matters. Exchange rates fluctuate throughout the day. If you deposit in the morning and withdraw in the evening, the rate might have moved against you. This is especially volatile during major economic events, like interest rate announcements or election results. The casino doesn’t care about your timing. They process the transaction at the rate available at the moment of processing. You have no control over this. The only strategy is to deposit and withdraw in the same currency, if possible, to eliminate the conversion entirely.
What Happens When a Credit Card Deposit Fails
A failed deposit is frustrating, but it’s not the end of the world. The first thing to check is your bank’s app. Most banks will show declined transactions in real-time. If the transaction is there, but marked as declined, the bank has blocked it. Call the bank’s fraud department and ask them to allow the transaction. They might lift the block temporarily, or they might ask you to verify your identity. Either way, the conversation is usually quick. The bank wants to help you spend money. They just want to make sure it’s you spending it.
If the transaction isn’t showing in your bank’s app, the problem is on the casino’s side. The payment gateway might be down, or the transaction might have timed out. In this case, try again in 15-30 minutes. If it still fails, contact the casino’s support team. They can check the transaction logs and see what happened. Sometimes, the issue is a simple technical glitch that’s resolved quickly. Other times, it’s a systemic problem with the processor that can take hours or days to fix. Patience is key.
The worst-case scenario is a “ghost” transaction. The money has left your account, but it hasn’t arrived at the casino. This happens when the transaction is interrupted between the bank and the casino’s processor. The money is in limbo. It’s not lost, but it’s not anywhere either. This is rare, but it does happen. The resolution process involves both the bank and the casino’s payment team. It can take 3-10 business days to sort out. During this time, the money is frozen. You can’t use it, and the casino can’t see it. It’s a black hole. The only thing you can do is wait and follow up daily with both parties.
Prevention is better than cure. Before depositing, make sure your card is enabled for online transactions. Some banks require you to activate this feature separately. Check your card’s expiry date and CVV. Make sure you’re entering the correct billing address. These are obvious things, but in the rush to deposit, they’re easily overlooked. A typo in the card number or the expiry date will cause a decline. Double-check everything before you hit submit. It takes two seconds and can save you a headache.
Millioner Casino Free Spins 2026: A Cynic’s Guide to Not Losing Your Shirt
The Future of Credit Card Gambling in Australia
The regulatory environment is tightening. The Australian government has been reviewing the Interactive Gambling Act, with a focus on payment blocking and consumer protection. There’s talk of a national self-exclusion register, mandatory loss limits, and stricter advertising rules. The banks are also under pressure to do more to block gambling transactions. The ACCC has been investigating the effectiveness of the current payment blocking measures. The consensus is that they’re not working well enough. The casinos are too good at circumventing them.
The rise of open banking could change the landscape. Open banking allows third-party providers to access your bank account data (with your permission) and initiate transactions on your behalf. This could enable new payment methods that bypass the traditional credit card network entirely. Imagine a system where you authorize a direct transfer from your bank account to the casino, with no card involved. The transaction would be faster, cheaper, and harder for the banks to block. It’s not here yet, but the infrastructure is being built.
Cryptocurrency is another wild card. As more Australians adopt crypto, casinos are increasingly offering it as a payment method. Crypto transactions are decentralized, meaning they can’t be blocked by banks or regulators. This makes them attractive for both players and casinos. The volatility is a drawback, but stablecoins like USDT and USDC are designed to address this. They’re pegged to the US dollar, so their value doesn’t fluctuate. If stablecoins gain mainstream adoption, they could become the preferred method for online gambling deposits. The credit card might eventually become a secondary option.
The credit card isn’t going anywhere soon. It’s too deeply embedded in the financial system. But its dominance in online gambling is being challenged by new technologies and tighter regulations. The casinos that adapt will survive. The ones that don’t will be left behind. For players, the message is clear: diversify your payment methods. Don’t rely on a single card. Have a backup plan. The landscape is shifting, and the players who are prepared will be the ones who thrive. The rest will be left complaining about declined transactions and frozen funds.
Can I use a prepaid credit card to deposit at an online casino?
Prepaid cards like Paysafecard work differently from standard credit cards. They’re not linked to your bank account, so there’s no risk of overspending. The downside is that they usually can’t be used for withdrawals. You’d need an alternative method, like a bank transfer, to cash out. Some casinos don’t accept prepaid cards at all, so check the banking page before you buy one. The convenience of anonymity comes with the inconvenience of a one-way street.
What happens if my credit card details are stolen at a casino?
Reputable casinos use encryption and tokenization to protect your card details. If a breach occurs, the casino is legally required to notify you and the relevant authorities. Your bank will likely cancel your card and issue a new one. Any unauthorized transactions can be disputed through the chargeback process. The risk is real, but it’s mitigated by choosing casinos with strong security credentials. Look for SSL encryption, PCI DSS compliance, and a reputable license. These are the minimum standards.
Do casinos report my winnings to the ATO?
Offshore casinos don’t report to the Australian Taxation Office. However, you’re legally required to declare all gambling winnings as income. If you win big, the ATO might ask questions, especially if the amount is inconsistent with your declared income. Keep records of your deposits and withdrawals. If you’re a recreational player, the tax implications are minimal. If you’re a professional gambler, the rules are different, and you should consult a tax professional. Ignorance is not a defence.
Can I set a deposit limit on my credit card at the casino?
Yes, most licensed casinos offer deposit limits as part of their responsible gambling tools. You can set daily, weekly, or monthly limits. Once you reach the limit, you can’t deposit more until the period resets. This is a useful tool for managing your bankroll, but it requires discipline to set up. Some players remove the limit when they’re on a losing streak, which defeats the purpose. The tool works only if you let it work.
Why was my credit card declined at a casino even though I have funds?
A decline doesn’t always mean you don’t have funds. It could be triggered by the bank’s fraud detection system, which flags unusual spending patterns. It could be that the casino’s merchant code is blocked by your bank. It could be a temporary technical issue with the payment gateway. The most common reason is that the transaction looks suspicious to the bank’s algorithm. Call your bank to verify. They can usually lift the block after a quick identity check. Don’t take it personally. The algorithm doesn’t know you. It’s just following its programming.
The entire payment ecosystem is a maze of intermediaries, each taking their cut and adding their own rules. Your credit card is just the first domino. Behind it are the issuing bank, the card network, the acquiring bank, the payment gateway, and the casino’s own financial department. Each one has its own fraud detection, its own fees, and its own processing times. When everything works, it’s seamless. When one link in the chain fails, the whole thing falls apart. The player is left wondering why their deposit didn’t go through, while five different entities point fingers at each other. It’s a system designed for efficiency, but it’s held together with duct tape and good intentions.
独自に開発した
タイピングソフトを販売しております。
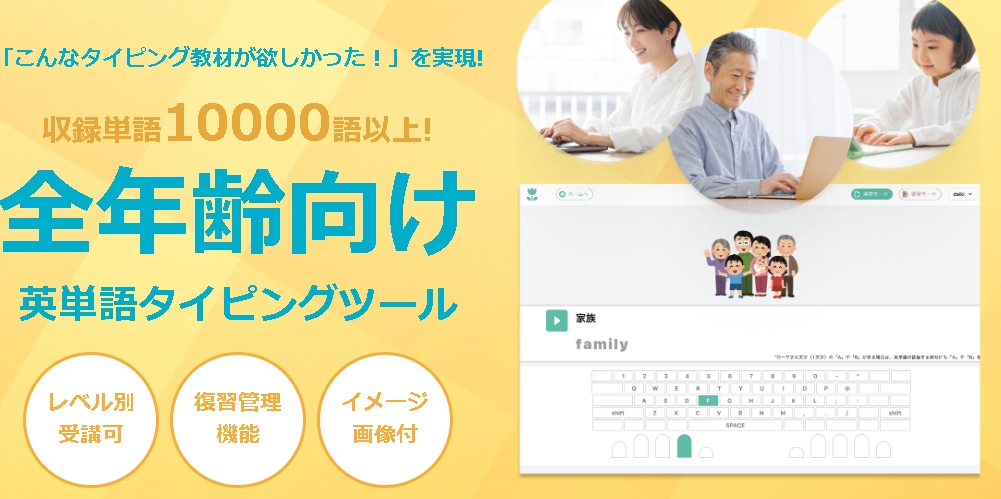
単語学習、聞き取り学習、タイピング練習はもちろん。
できなかった部分だけを重点的に学習できるように復習機能もついています。
また、中1レベルからTOEIC900点クラスまで網羅している為
無料お試し版がご利用いただけますので