Casinos That Accept Mastercard Australia 2026: The Only Guide You Need Before You Lose Your Money
Let’s get one thing straight right off the bat. You’re not here because you love Mastercard. You’re here because you want to put money into an online casino, and your Visa card just got declined for the third time this month. The Australian banking system has a peculiar relationship with gambling transactions. It’s like a bouncer who lets you into the club but then cuts off your bar tab after two drinks. Mastercard, for reasons that make sense only to their internal risk algorithms, remains a slightly more reliable option for deposits at many offshore casinos that cater to Australian players. But “reliable” is a relative term in this industry.
The year 2026 brings its own set of headaches. Regulatory pressure is tightening, payment processors are getting skittish, and the casinos themselves are constantly shuffling their accepted methods like a dealer with a nervous tic. Finding a casino that accepts Mastercard in Australia isn’t the hard part. The hard part is finding one that won’t eat your deposit in fees, hold your withdrawal for three weeks while asking for your great-grandmother’s birth certificate, and then blame “technical issues” when you complain. This guide is about cutting through that noise. We’ll look at how Mastercard actually works for gambling transactions, what the real costs are, and how to spot a casino that’s worth your time and your AUD.
We’re not going to pretend this is a magic solution. There is no such thing. Using Mastercard at an online casino is a transaction, not a miracle. The casinos are businesses. They’re not charities. And that “free” bonus they’re offering? It’s a marketing expense with strings attached, calculated to the last cent to ensure they come out ahead. Your job is to understand the math, know the risks, and make a decision with your eyes open. Let’s begin.
How Mastercard Transactions Actually Work at Australian Online Casinos
The mechanics are deceptively simple. You enter your 16-digit card number, expiry date, and CVV. The casino’s payment gateway sends an authorization request to Mastercard’s network. Mastercard then contacts your issuing bank—in Australia, that’s likely one of the Big Four: Commonwealth, Westpac, ANZ, or NAB. The bank runs its own fraud and gambling transaction filters. If the charge clears, the funds move from your bank account to the casino’s merchant account, usually via an intermediary processor located in a jurisdiction with favorable gambling laws. The entire process, from click to casino balance, typically takes between 30 seconds and 5 minutes. But that’s the ideal scenario.
25 Free Spins No Deposit Australia 2026: The Math Behind the “Free” Lunch
In reality, the Australian Banking Association’s voluntary code of practice allows banks to block or flag gambling transactions. This isn’t a law, but banks follow it to manage risk. Some banks code casino deposits as “cash advances,” which come with immediate interest charges—often between 2% and 5% of the transaction amount—and no interest-free period. A $100 deposit could cost you $105 before you’ve even placed a bet. Others treat it as a standard purchase, but may still trigger a fraud alert, requiring you to confirm the transaction via SMS. This inconsistency is the core problem. There’s no universal rule. Your experience depends entirely on which bank issued your Mastercard.
The casino side adds another layer. Most offshore casinos don’t process Mastercard payments directly. They use third-party processors like Nuvei, PayOp, or InPay. These intermediaries bundle transactions from multiple casinos and route them through acquiring banks in Malta, Curaçao, or the Isle of Man. This indirect routing is why your bank statement might show a charge from “MERIDIAN GAMING LTD” instead of the casino’s name. It’s also why transactions sometimes fail without explanation—the processor’s risk engine might flag your card based on patterns, location, or even the time of day. A Tuesday morning deposit from Sydney might go through, while a Saturday night attempt from the same card gets blocked.
And here’s a detail most guides skip: the merchant category code (MCC) matters. Gambling transactions fall under MCC 7995. Mastercard’s own rules require merchants to use this code, but many casinos deliberately use MCC 7999 (miscellaneous recreation services) or even 5967 (direct marketing—inbound telemarketing) to avoid detection. This practice is technically against Mastercard’s terms, but enforcement is sporadic. When a casino uses a misleading MCC, your bank is less likely to block the transaction, but you also lose some consumer protections if a dispute arises. It’s a gamble within a gamble, and the house always wins both.
Legal Status of Online Gambling and Mastercard Use in Australia
Australia’s gambling laws are a patchwork quilt stitched together by state and federal politicians who understand neither the internet nor gambling. The Interactive Gambling Act 2001 (IGA) makes it illegal for operators to offer online casino games and poker to Australian residents. It does not, however, make it illegal for individual Australians to play at offshore casinos. This legal gray area is the foundation of the entire market. The casinos operate from jurisdictions like Curaçao, Malta, or Gibraltar. They accept Australian players. And Australian players use Mastercard to fund their accounts. Everyone involved is technically breaking some rule, but enforcement against individual players is virtually nonexistent.
The Australian Communications and Media Authority (ACMA) has the power to block websites and issue fines to operators, but its reach is limited. In 2024, ACMA added over 500 offshore gambling domains to its blocklist. Players using VPNs or simply accessing casinos through alternative domains bypass these blocks easily. The banks, meanwhile, operate under the Australian Prudential Regulation Authority (APRA) and the Australian Transaction Reports and Analysis Centre (AUSTRAC). They have obligations to monitor for money laundering and problem gambling, which is why they sometimes block gambling transactions. But there’s no law that says a bank must decline a Mastercard deposit to an offshore casino. It’s a risk management decision, not a legal mandate.
The tax implications are straightforward, if you’re a recreational player. Gambling winnings are not taxable in Australia. The Australian Taxation Office (ATO) considers gambling a recreational activity, not a source of income. This applies whether you win at a local pokies machine or at an offshore online casino. However, if you’re a professional gambler—meaning you treat it as a business, have a consistent profit, and operate with a degree of organization—the ATO might reclassify your winnings as assessable income. The line between “recreational” and “professional” is blurry, and the ATO has its own criteria. For the vast majority of players using Mastercard at online casinos, taxes aren’t a concern. The real cost is in the fees and the odds.
The future of this legal framework is uncertain. The 2023 review of the IGA recommended stricter enforcement against offshore operators and potentially criminalizing the use of their services by Australian residents. If implemented, this could change the landscape dramatically. But as of 2026, the status quo remains: players can access offshore casinos, use Mastercard for deposits, and operate in a legal gray zone. The casinos know this. The banks know this. And you should know it too, because it affects your consumer rights, your dispute options, and your overall risk profile.
Top Mastercard Casinos for Australian Players in 2026
Choosing a casino is less about finding the “best” one and more about avoiding the worst ones. The market is saturated with operators who look identical on the surface—same game libraries, same bonus structures, same slick websites. The differences are in the fine print, the payment processing reliability, and the speed at which they actually pay out your winnings. We’ve evaluated casinos based on their Mastercard acceptance rate for Australian cards, fee transparency, withdrawal processing times, and regulatory standing. The following list isn’t an endorsement. It’s a starting point for your own due diligence.
These operators have demonstrated consistent Mastercard processing for Australian players, with transaction success rates above 80% based on aggregated user reports. They also maintain transparent fee structures and don’t bury withdrawal conditions in 50-page terms of service documents. But remember: a casino’s reputation can change overnight. New management, new payment processors, new regulatory pressures—all can affect your experience. What works today might not work tomorrow. That’s why we focus on the criteria, not just the names.
| Operator | Mastercard Deposit Fee | Min. Deposit (AUD) | Withdrawal Time (Mastercard) | License |
|---|---|---|---|---|
| Jackpot City | None (casino-side) | $10 | 2-5 business days | Malta Gaming Authority |
| Spin Casino | None (casino-side) | $10 | 2-5 business days | Malta Gaming Authority |
| Royal Vegas | None (casino-side) | $10 | 2-5 business days | Malta Gaming Authority |
| PlayAmo | None (casino-side) | $15 | 1-3 business days | Curaçao eGaming |
| Ignition Casino | None (casino-side) | $20 | 1-3 business days | Curaçao eGaming |
The “None (casino-side)” fee designation is important. It means the casino doesn’t charge you a fee for depositing with Mastercard. However, your bank almost certainly does. As mentioned earlier, many Australian banks treat gambling deposits as cash advances, charging a fee of 2-5% plus immediate interest. A $100 deposit could cost you $105-$110 in total. This isn’t the casino’s fault, but it’s a cost you need to factor into your bankroll management. Some casinos mitigate this by offering alternative payment methods like POLi or BPAY, which are processed as bill payments and avoid cash advance fees. But if you’re set on using Mastercard, expect to pay the bank’s premium.
The withdrawal times listed are typical ranges, not guarantees. Mastercard withdrawals are slower than deposits because they require additional verification steps. The casino must confirm your identity, ensure you’ve met any bonus wagering requirements, and then initiate a refund to your card. This refund is technically a “credit” transaction, which banks process differently than debits. Some Australian banks take 3-5 business days to post Mastercard credits, while others can take up to 10. The casino’s processing time is only part of the equation. Your bank’s internal procedures matter just as much.
The licenses listed are the primary regulatory bodies overseeing these operators. A Malta Gaming Authority (MGA) license is generally considered more stringent than a Curaçao eGaming license. MGA requires operators to maintain player funds in segregated accounts, submit to regular audits, and provide clear dispute resolution processes. Curaçao’s oversight is lighter, with fewer requirements for player protection. Neither license guarantees a casino will treat you fairly, but an MGA license provides more recourse if they don’t. Always check the license number on the regulator’s website—it should be displayed in the casino’s footer, and it should match.
Deposit and Withdrawal Limits, Fees, and Processing Times
Mastercard deposits at Australian-facing casinos typically have a minimum of $10-$20 AUD and a maximum of $1,000-$5,000 per transaction. These limits are set by the casino’s payment processor, not by Mastercard itself. The maximum can often be increased by verifying your account and providing additional documentation—proof of address, source of funds, a copy of your driver’s license. This verification process is a regulatory requirement for casinos licensed in Malta or Gibraltar, and it’s a good sign if a casino asks for it upfront. Casinos that don’t verify players until withdrawal time are often the ones that create problems later.
Withdrawal limits are more complex. Most casinos impose a weekly or monthly cap on withdrawals, especially for players who haven’t reached VIP status. A typical limit might be $4,000-$5,000 per week for standard players. If you win a progressive jackpot of $50,000, you won’t get it all at once. The casino will pay it out in installments, often $5,000 per week, which means it could take 10 weeks to receive your full winnings. This isn’t unusual, but it’s rarely disclosed prominently. Always check the withdrawal policy before you deposit. A casino that hides its withdrawal limits in the terms and conditions is a casino that expects you to be unhappy about them.
Pokies Parlour Casino Australia 2026: A Veteran’s Guide to the Digital Pokie Parlor
The fee structure is where things get murky. The casino might not charge a fee for deposits or withdrawals, but Mastercard’s network imposes interchange fees on the merchant. These fees are typically 1.5-2.5% of the transaction value, and while the casino absorbs them on deposits, they sometimes pass them on to players for withdrawals. A $1,000 withdrawal might incur a $25 fee, deducted from your payout. Again, this varies by casino. The ones in our table above don’t charge withdrawal fees for Mastercard, but others do. Read the banking page carefully. If it’s not explicitly stated, assume there’s a fee and ask customer support before you withdraw.
Processing times for withdrawals follow a predictable pattern. First, there’s the casino’s internal processing, which can take 24-72 hours. During this time, the casino’s finance team reviews your account, checks for bonus abuse, and ensures all wagering requirements are met. Then there’s the payment processor’s handling time, which adds another 1-2 business days. Finally, your bank’s processing time adds 2-5 business days. From request to funds in your account, the total is typically 3-10 business days. Weekends and public holidays don’t count. If you request a withdrawal on a Friday evening, don’t expect to see the money until the following week at the earliest.
What Games Can You Play with Mastercard Deposits?
The game selection at Mastercard-accepting casinos is identical to the overall game library. The payment method doesn’t restrict which games you can play. What matters is the casino’s game provider partnerships. The top-tier casinos work with providers like Microgaming, NetEnt, Play’n GO, and Evolution Gaming. These companies supply the pokies, table games, and live dealer experiences that form the core of any serious casino’s offering. The quality of these providers varies, but the big names have earned their reputation through years of consistent performance and fair RNG (random number generator) certification.
Pokies dominate the Australian market, and for good reason. They’re simple, fast, and offer the illusion of big wins with minimal effort. The average RTP (return to player) for online pokies ranges from 94% to 97%, depending on the game and the casino’s configuration. Some casinos allow providers to offer lower RTP versions of popular games, which increases the house edge. This practice is legal but shady. A casino that offers the 94% RTP version of a game when a 96% version exists is choosing to take more of your money. You won’t find this information on the casino’s website. You need to check the game’s information panel or the provider’s documentation.
Table games like blackjack, roulette, and baccarat are available at most casinos, but the experience varies significantly. The best casinos offer multiple variants of each game, with different rule sets and betting limits. Blackjack, for example, might come in Classic, European, Vegas Strip, and Atlantic City variants, each with slightly different rules that affect the house edge. A knowledgeable player can reduce the house edge in blackjack to under 0.5% with optimal strategy. In roulette, the difference between European (single zero) and American (double zero) wheels is significant—the house edge jumps from 2.7% to 5.26%. Always choose European roulette if it’s available.
Live dealer games have become the gold standard for players who want an authentic casino experience without leaving their couch. Providers like Evolution Gaming stream real dealers from studios in Malta, Latvia, and the Philippines. The games are played in real time, with actual cards and wheels. The house edge is the same as the digital versions, but the minimum bets are higher—typically $5-$10 per hand or spin, compared to $0.10-$1 for digital games. Live dealer games also consume more data, so a stable internet connection is essential. A dropped connection during a live blackjack hand doesn’t pause the game. The dealer continues, and your bet is lost. That’s the risk you take for authenticity.
Comparison of Mastercard with Other Payment Methods for Australian Players
Mastercard is one of several options for funding your casino account. The alternatives each have their own advantages and disadvantages, and the best choice depends on your priorities. If speed is your primary concern, cryptocurrency deposits are fastest—typically confirmed within 10 minutes. If privacy is your priority, prepaid vouchers like Paysafecard offer anonymity. If you want to avoid cash advance fees, POLi or BPAY are processed as bill payments. But Mastercard offers a balance of convenience, widespread acceptance, and consumer protection that few other methods can match.
| Payment Method | Deposit Speed | Withdrawal Speed | Fees (Typical) | Privacy Level |
|---|---|---|---|---|
| Mastercard | Instant to 5 min | 2-10 business days | 0% casino-side, 2-5% bank-side | Low (bank sees transaction) |
| POLi | ||||
| POLi | Instant | N/A (deposit only) | None | Medium (bank sees transaction) |
| Bitcoin | 10-60 min | 1-24 hours | Network fee (variable) | High (pseudonymous) |
| Paysafecard | Instant | N/A (deposit only) | None (but 4% after 12 months) | High (prepaid voucher) |
| Bank Transfer | 1-3 business days | 3-7 business days | None (but bank may charge) | Low (direct bank record) |
POLi is a favorite among Australian players because it bypasses the credit card gambling block entirely. It’s a direct bank transfer system that works with most major Australian banks. You log in to your bank through the POLi interface, confirm the payment, and the funds are transferred instantly. The casino never sees your card details, and your bank sees it as a bill payment, not a gambling transaction. The downside? POLi is deposit-only. You can’t withdraw to a POLi account. So you’ll need an alternative method for cashing out, which brings you back to Mastercard or bank transfer.
Cryptocurrency offers the fastest withdrawals and the highest privacy, but it comes with its own set of risks. The value of Bitcoin can fluctuate 5-10% in a single day. A $1,000 withdrawal in Bitcoin might be worth $950 or $1,050 by the time it reaches your wallet, depending on market conditions. The casinos that accept crypto typically offer Bitcoin, Ethereum, and Litecoin. They process crypto withdrawals much faster than traditional methods—often within an hour—because there’s no banking intermediary. But you need a crypto wallet, and you need to understand how blockchain transactions work. A mistake in a wallet address means your money is gone forever. No customer support can help you.
Paysafecard is a prepaid voucher system that you can purchase with cash at retail locations across Australia. You buy a voucher for a fixed amount—typically $10, $25, $50, or $100—and enter the 16-digit PIN at the casino’s cashier. It’s anonymous in the sense that you’re not sharing bank or card details, but the casino still knows your IP address and device fingerprint. The main limitation is that Paysafecard is deposit-only, and there’s a 4% inactivity fee if you don’t use the voucher within 12 months. For players who want to control their spending, prepaid vouchers are useful. You can only lose what you’ve loaded onto the card. That’s a feature, not a bug.
New Casinos Accepting Mastercard in Australia: What to Watch For
The online casino market sees dozens of new operators launch every year. Most don’t survive past their first 18 months. The ones that do have usually secured proper licensing, established reliable payment processing, and built a player base through aggressive marketing. New casinos often accept Mastercard because it’s the easiest payment method to integrate—most payment processors offer it as a default option. But accepting Mastercard and processing it reliably are two different things.
New casinos have a higher risk of payment issues. Their merchant accounts are fresh, which means they haven’t established a track record with their payment processor. Processors monitor new merchants closely, and if they detect unusual patterns—like a sudden spike in deposits from Australian cards—they may freeze the account. This can result in deposits that go through on your end but never arrive at the casino. The casino blames the processor, the processor blames the bank, and you’re left waiting for a resolution that may never come. This is why experienced players often wait 6-12 months before trying a new casino. Let someone else be the guinea pig.
New casinos also tend to offer larger welcome bonuses to attract players. A typical offer might be a 200% match on your first deposit, up to $2,000, plus 200 free spins. The numbers look impressive, but the wagering requirements are usually brutal—40x to 60x the bonus amount. A $100 deposit with a 200% match gives you $300 to play with, but you need to wager $12,000 to $18,000 before you can withdraw any winnings from the bonus. The house edge on pokies ensures that most players will lose their entire balance before meeting these requirements. The bonus isn’t a gift. It’s a marketing tool designed to keep you playing longer.
The regulatory status of new casinos is another concern. Many launch with a Curaçao license, which is quick and cheap to obtain but offers minimal player protection. Some operate without any license at all, relying on the legal gray area of offshore gambling. If you deposit at an unlicensed casino and they refuse to pay your winnings, you have no regulatory body to complain to. Your only option is to post negative reviews and hope the casino cares about its reputation. Some do. Many don’t. The safest approach is to stick with casinos that have been operating for at least two years and hold a license from a recognized authority like the MGA or the UK Gambling Commission.
Responsible Gambling and Mastercard: Setting Your Limits
Using a credit card for gambling is inherently risky. Unlike a debit card, which draws from funds you already have, a credit card allows you to spend money you don’t have. This is why the UK banned credit card gambling in 2020, and why Australia’s banks are increasingly cautious about processing gambling transactions on credit cards. Mastercard itself doesn’t distinguish between credit and debit cards at the merchant level, but your bank does. Deposits made with a credit card may be treated as cash advances, with higher fees and immediate interest charges. Deposits made with a debit card draw directly from your bank account balance.
The responsible gambling tools offered by casinos are a mixed bag. Most reputable casinos allow you to set deposit limits—daily, weekly, or monthly. Once you hit the limit, you can’t deposit more until the period resets. You can also set loss limits, session time limits, and self-exclusion periods. These tools are mandated by regulators like the MGA, and casinos that don’t offer them risk losing their license. But the effectiveness of these tools depends entirely on your willingness to use them. A limit you can easily remove with a single click isn’t much of a limit. The best approach is to set your limits when you’re in a clear-headed state, and then don’t touch them.
Self-exclusion is the nuclear option. If you feel you can’t control your gambling, you can exclude yourself from a casino for a period of 6 months to 5 years. During this period, the casino is legally required to prevent you from accessing your account. Some casinos participate in multi-operator self-exclusion schemes like GAMSTOP (UK) or BetStop (Australia), which block you from all participating casinos with a single registration. But these schemes have gaps. Offshore casinos that don’t hold an Australian license aren’t required to participate. If you self-exclude from one casino, you can still deposit at another. The system works only if you’re honest with yourself about the extent of your problem.
The financial reality of gambling is brutal. The house always has an edge, and that edge ensures that over time, the casino will take more money from you than it pays out. On pokies, the house edge is typically 3-6%. On table games, it’s 1-5% depending on the game and your strategy. Over 1,000 bets of $10 each, you’re statistically likely to lose $300-$600. That’s not a prediction for any single session—it’s the mathematical expectation over time. The only way to win consistently is to stop playing. But if you’re going to play, set a budget, stick to it, and treat the money as the cost of entertainment. Don’t chase losses. Don’t borrow to play. And don’t believe anyone who tells you there’s a system that beats the house.
How We Evaluate and Rank Mastercard Casinos for Australian Players
Our evaluation process is based on measurable criteria, not subjective impressions. We don’t accept payment for rankings, and we don’t let casinos influence our assessments. The primary factors we consider are payment processing reliability, regulatory standing, game fairness, and customer support responsiveness. Each factor is weighted based on its importance to the average player. Payment processing reliability gets the highest weight because it directly affects your ability to deposit and withdraw funds.
To assess payment processing reliability, we analyze aggregated user reports from multiple sources—gambling forums, review sites, and direct player feedback. We look at the percentage of successful Mastercard deposits, the average time for withdrawals to reach players’ accounts, and the frequency of payment-related complaints. A casino with a 90%+ success rate for Mastercard deposits and withdrawals processed within 5 business days scores well. A casino with frequent reports of declined deposits, delayed withdrawals, or unresponsive support scores poorly. We also verify that the casino’s stated processing times match the actual experience reported by players.
Regulatory standing is evaluated by checking the casino’s license status with the relevant authority. We verify the license number on the regulator’s website, confirm that it’s active, and check for any enforcement actions or player complaints filed with the regulator. A casino with a clean regulatory record scores higher than one with a history of sanctions or unresolved disputes. We also consider the strictness of the regulatory framework. An MGA license requires more stringent player protection measures than a Curaçao license, so casinos licensed in Malta receive a higher baseline score for this factor.
Game fairness is assessed by checking for RNG certification from independent testing agencies like eCOGRA, iTech Labs, or GLI. These agencies audit the random number generators used by casino games to ensure they produce statistically random outcomes. A casino that displays an eCOGRA seal on its website has submitted to regular audits and publishes the results. This transparency is a positive signal. We also check whether the casino offers games from reputable providers with known fair RTP settings. Casinos that use lesser-known providers or don’t disclose their RTP rates receive lower scores for this factor.
Frequently Asked Questions About Mastercard Casinos in Australia
Can I use my Australian Mastercard at offshore online casinos?
Yes, you can use an Australian Mastercard at offshore online casinos, but success depends on your bank’s policies. Some Australian banks automatically decline gambling transactions, while others allow them but treat them as cash advances with additional fees. The Interactive Gambling Act 2001 doesn’t prohibit individual Australians from playing at offshore casinos, so the transaction itself isn’t illegal. However, your bank may have its own policies that restrict or flag gambling-related charges, which can result in declined transactions even if the casino accepts Mastercard.
Are there fees for using Mastercard at online casinos?
The casino typically doesn’t charge a fee for Mastercard deposits, but your bank almost certainly does. Most Australian banks classify gambling deposits as cash advances, which carry a fee of 2-5% of the transaction amount plus immediate interest charges with no interest-free period. A $100 deposit could cost you $105-$110 in total fees and interest. Withdrawal fees vary by casino—some charge nothing, while others deduct a percentage for processing. Always check both the casino’s fee schedule and your bank’s cash advance terms before making a transaction.
How long do Mastercard withdrawals take at Australian casinos?
Mastercard withdrawals typically take 3-10 business days from request to funds in your account. This includes the casino’s internal processing time (24-72 hours), the payment processor’s handling time (1-2 business days), and your bank’s posting time (2-5 business days). Weekends and public holidays don’t count toward these timelines. Some casinos have a pending period during which you can reverse your withdrawal—this is a red flag, as it encourages impulsive play. Look for casinos that process withdrawals immediately without a pending period.
Is it safe to enter my Mastercard details at online casinos?
It’s as safe as any online transaction, provided the casino uses proper security measures. Look for SSL encryption (the padlock icon in your browser’s address bar), PCI DSS compliance (which ensures the casino handles card data securely), and a valid gambling license from a recognized authority. No system is completely immune to data breaches, but casinos with strong security practices significantly reduce the risk. Avoid casinos that don’t display security information or that ask for your card details via email or chat—these are signs of a scam operation.
Can I reverse a Mastercard deposit if I lose too much?
You can request a chargeback through Mastercard’s dispute resolution process, but success is unlikely if the transaction was legitimate. Chargebacks are designed for unauthorized transactions or goods not received, not for gambling losses. If you deposited at a licensed casino, played games, and lost, the transaction was authorized and the service was delivered. Filing a fraudulent chargeback can result in your account being flagged by Mastercard, making it harder to use your card for legitimate transactions in the future. The responsible approach is to set deposit limits before you start playing, not to rely on chargebacks after the fact.
Do all online casinos that accept Australian players support Mastercard?
Not all, but most do. Mastercard is one of the most widely accepted payment methods at offshore casinos, alongside Visa, Bitcoin, and e-wallets like Skrill and Neteller. Some casinos have moved away from credit card payments due to regulatory pressure or high processing fees, but they’re in the minority. If a casino doesn’t accept Mastercard, it usually offers alternative methods like POLi, BPAY, or cryptocurrency. The key is to check the casino’s banking page before you register to ensure your preferred payment method is supported for both deposits and withdrawals.
The Real Cost of “Free” Bonuses at Mastercard Casinos
Every online casino offers bonuses. Welcome bonuses, deposit matches, free spins, cashback offers, loyalty rewards—the marketing departments never run out of ideas. But these bonuses aren’t free. They’re calculated expenses designed to acquire and retain players, and the terms attached to them ensure the casino comes out ahead in the long run. Understanding the math behind these offers is essential if you want to make informed decisions about where to play and how much to deposit.
The most common offer is a deposit match bonus, typically 100-200% of your first deposit, up to a specified maximum. A 100% match on a $100 deposit gives you $200 to play with. Sounds great. But the bonus comes with wagering requirements—a multiplier that determines how much you need to bet before you can withdraw any winnings derived from the bonus. A 40x wagering requirement on a $100 bonus means you need to place $4,000 in bets before the bonus converts to withdrawable cash. The house edge on pokies is typically 4%, so over $4,000 in bets, you’re statistically expected to lose $160. That’s more than the original bonus. The casino has already won.
Free spins are even more deceptive. A casino might offer 200 free spins as part of a welcome package. Each spin is valued at $0.10, so the total “value” is $20. But the winnings from free spins are usually credited as bonus funds, subject to the same wagering requirements as deposit match bonuses. If you win $50 from your free spins and the wagering requirement is 40x, you need to bet $2,000 before you can withdraw that $50. And the house edge ensures you’ll lose a portion of that $2,000 along the way. The “free” spins are a marketing hook, not a gift. They’re designed to get you playing, not to get you winning.
Cashback offers return a percentage of your losses over a specified period—typically 5-20% of net losses. A 10% cashback on $500 in losses gives you $50 back. But the cashback is usually paid as bonus funds with wagering requirements. And the act of offering cashback encourages you to keep playing to “earn” the cashback, which often results in additional losses. It’s a psychological trick: the casino gives you a small consolation prize to keep you at the table. The math always favors the house. The only winning move is to recognize that these bonuses are advertising, not charity, and adjust your expectations accordingly.
Technical Issues and Troubleshooting Mastercard Deposits
Failed deposits are the most common complaint among Australian players using Mastercard. The reasons vary, but the most frequent are insufficient funds, bank-imposed gambling blocks, and mismatched billing information. If your deposit is declined, the first step is to check your bank’s mobile app or call their customer service line. Some banks allow you to temporarily lift gambling blocks through their app—Commonwealth Bank’s CommBank app, for example, has a “gambling lock” feature that you can toggle on and off. If the block is at the bank level, no amount of retrying will help until you address it there.
Mismatched billing information is another common issue. The name and address you enter at the casino’s cashier must match exactly what your bank has on file. Even a small discrepancy—a typo in your street name, an old address, a middle initial omitted—can cause the transaction to fail. This is part of Mastercard’s Address Verification System (AVS), which compares the billing address you provide with the address on file with your bank. If they don’t match, the transaction is declined. Double-check your details before submitting, and make sure your bank has your current address.
3D Secure authentication can also cause problems. Mastercard’s SecureCode system (now called Mastercard Identity Check) requires you to verify your identity with a one-time password sent to your phone orauthenticator app. If you haven’t set this up, or if your phone number has changed, the verification step will fail. The transaction gets stuck in limbo—your bank has authorized it, but the casino hasn’t received confirmation. The funds are frozen for 24-48 hours before being released back to your account. During that time, you can’t use those funds for anything else. It’s a temporary hold, not a charge, but it feels like a loss when you’re trying to play.
Technical issues with Mastercard withdrawals are less common but more frustrating. The most frequent problem is a “refund failed” status, which means the casino attempted to credit your card but the transaction was rejected by your bank. This can happen if your card has expired, if your account has been closed, or if your bank doesn’t accept credit refunds to debit cards. Some Australian banks require refunds to go to the original payment method, but if you deposited with a credit card and now want the withdrawal on your debit card, the mismatch causes a failure. The casino will ask you to provide an alternative withdrawal method, which adds days to the process.
Another technical headache is the “transaction not found” error. This occurs when the casino’s payment processor can’t locate your deposit in their system, usually because of a communication breakdown between the processor and Mastercard’s network. Your bank shows the charge, but the casino shows no record of it. The funds are in transit—neither in your account nor in the casino’s. Resolution requires the casino to file a trace request with their processor, which can take 5-10 business days. During that time, you’re stuck. You can’t play, and you can’t get your money back. The only thing you can do is wait and hope the trace finds your money.
Preventing these issues starts with preparation. Use a card that matches your current name and address. Ensure your bank hasn’t enabled gambling blocks. Set up 3D Secure authentication before you need it. And keep records of every transaction—screenshot the confirmation screen, save the transaction ID, note the date and time. If something goes wrong, this documentation is your only leverage. Casinos and banks are more likely to resolve issues quickly when you can provide specific details rather than vague complaints. It’s tedious, but it’s the price of doing business in a system that wasn’t designed with your convenience in mind.
Mastercard VIP Programs and Casino Loyalty Schemes: Worth the Hype?
Mastercard itself offers several card tiers—Standard, World, and World Elite—each with its own benefits. The World and World Elite tiers include perks like airport lounge access, travel insurance, and purchase protection. Some casinos offer enhanced benefits for players using these premium cards, such as higher deposit limits, faster withdrawals, or exclusive bonuses. But these casino-specific perks are rare and usually reserved for high-volume players. The average player using a standard Mastercard won’t see any special treatment from the casino based on their card tier.
Casino loyalty programs are a different beast entirely. They’re designed to reward consistent play with points that can be redeemed for bonus funds, free spins, or merchandise. The structure is typically tiered—bronze, silver, gold, platinum—with higher tiers offering better conversion rates and exclusive perks. A bronze player might earn 1 point for every $10 wagered, while a platinum player earns 1 point for every $5. But the points are almost always redeemable only as bonus funds with wagering requirements. A loyalty reward of $50 in bonus funds with a 30x wagering requirement means you need to bet $1,500 before you can withdraw it. The house edge ensures you’ll lose a portion of that $1,500, often more than the $50 reward.
The VIP programs at casinos are where the marketing really shines. They dangle the prospect of “exclusive” treatment—personal account managers, faster withdrawals, higher limits, invitations to special events. The reality is less glamorous. A personal account manager is usually a customer support agent with a slightly larger caseload. Faster withdrawals might mean 24 hours instead of 48. Higher limits are nice if you’re depositing thousands, but irrelevant if you’re playing with hundreds. The invitations to events are often for online tournaments with modest prize pools, not all-expenses-paid trips to Monaco. The VIP program is a retention tool, designed to make you feel valued so you keep playing. It’s a “free” lollipop at the dentist—you’re still in the chair.
The math of loyalty programs rarely works in the player’s favor. To reach gold status at a typical casino, you might need to wager $50,000 in a month. At a 4% house edge, that’s an expected loss of $2,000. The gold status might give you a 10% boost in point accumulation and a $100 monthly bonus with 25x wagering. The total value of those perks is maybe $200-$300, depending on your play style. You’ve spent $2,000 in expected losses to gain $200 in perks. That’s a 10% return on investment, which sounds okay until you realize you could have just kept the $2,000 and not played at all. The loyalty program rewards loyalty to the casino, not to your bank account.
Mobile Gaming with Mastercard: Apps, Browser Play, and Security
Most Australian players access casinos through their phones. The mobile experience has improved dramatically in recent years—responsive design, touch-optimized interfaces, and dedicated apps have made mobile gambling nearly identical to desktop. Mastercard deposits work seamlessly on mobile, with the same security protocols as desktop transactions. The casino’s cashier page is optimized for smaller screens, and the 3D Secure verification process is typically handled through your banking app, which is already on your phone. The convenience is undeniable, but so are the risks.
Mobile gambling removes the friction between impulse and action. You can deposit and play from anywhere—on the couch, on the bus, during a boring meeting. This accessibility is a feature for the casino and a risk for the player. Studies have shown that mobile gamblers are more likely to chase losses and exceed their budgets, simply because the barrier to placing another bet is so low. A desktop player has to be at their computer. A mobile player just has to reach for their phone. The ease of access is a double-edged sword, and it cuts the player more often than the casino.
Security on mobile is generally strong, but it depends on your habits. Casinos use the same SSL encryption on mobile as on desktop, and Mastercard’s security protocols apply regardless of device. The risk comes from the device itself. If your phone is unlocked and someone accesses it, they can deposit and play using your saved card details. Most casinos require a password or biometric authentication to log in, but once you’re in, the cashier is often accessible without additional verification. Setting a PIN or requiring biometric authentication for transactions adds a layer of protection. It’s a small inconvenience that can prevent a large problem.
Dedicated casino apps versus browser play is a common debate. Apps offer slightly faster loading times and push notifications for promotions, but they require storage space and may not be available in your app store due to gambling restrictions. Browser play works on any device with a modern browser and doesn’t require installation. The game selection and payment options are identical. The security is the same. The choice comes down to personal preference. If you value convenience and don’t want another app on your phone, browser play is fine. If you want the fastest possible experience and don’t mind the extra step of downloading, go with the app. Just remember to set deposit limits, regardless of how you access the casino.
Dispute Resolution: What to Do When a Mastercard Casino Won’t Pay
The worst-case scenario in online gambling isn’t losing a bet. It’s winning a bet and not getting paid. It happens more often than casinos like to admit, and the reasons range from “verification pending” to “bonus terms violated” to outright silence. When a casino refuses to pay your winnings, you have several options, but none of them are quick or guaranteed. The first step is always to contact the casino’s customer support and ask for a specific reason for the delay or refusal. Vague responses like “your account is under review” are red flags. You need a concrete explanation and a timeline for resolution.
If the casino’s support team can’t or won’t resolve the issue, your next step is to escalate to the casino’s regulatory authority. Casinos licensed by the Malta Gaming Authority (MGA) have a formal complaints procedure. You can file a complaint through the MGA’s website, providing documentation of your issue—screenshots of the casino’s response, transaction records, and copies of the relevant terms and conditions. The MGA will investigate and can compel the casino to pay if they find in your favor. Casinos licensed in Curaçao have a similar process, but it’s less structured and the enforcement is weaker. If the casino is unlicensed, you have no regulatory body to appeal to.
Mastercard’s chargeback process is another option, but it’s a last resort. A chargeback is a reversal of a credit card transaction, initiated by the cardholder through their bank. To file a chargeback, you need to prove that the transaction was unauthorized, that the goods or services weren’t delivered, or that the merchant violated their terms. For gambling transactions, this is difficult. You authorized the deposit. You played the games. The casino delivered the service. The fact that they won’t pay your winnings doesn’t necessarily qualify as a chargeback under Mastercard’s rules. Filing a fraudulent chargeback can result in your account being flagged, making it harder to use your card for legitimate transactions in the future.
Public pressure is sometimes effective. Posting detailed, factual complaints on gambling forums like CasinoMeister or AskGamblers can get a casino’s attention. Casinos care about their reputation, and a well-documented public complaint can be more damaging than a regulatory investigation. But this approach requires patience and persistence. Casinos often respond to public complaints by offering a partial settlement or requesting you remove the post. Don’t accept a settlement that doesn’t cover your full winnings, and don’t remove your post until the issue is fully resolved. The power of public pressure lies in its permanence.
The most important thing is documentation. Keep records of every transaction, every communication with the casino, and every response you receive. Screenshot the casino’s terms and conditions at the time you registered, because casinos sometimes change their terms retroactively. Save emails, chat transcripts, and transaction IDs. If you end up in a dispute, this documentation is your evidence. Without it, you’re just another disgruntled player making unverifiable claims. With it, you have a case that regulators, forums, and chargeback processors can evaluate objectively.
The Future of Mastercard Gambling Transactions in Australia
The regulatory landscape for online gambling in Australia is shifting. The government has signaled its intention to strengthen enforcement against offshore operators, potentially including criminal penalties for players who use their services. If implemented, this could make Mastercard transactions to offshore casinos riskier—not because Mastercard would block them, but because banks would be more aggressive in declining them. The banks are already cautious; stricter laws would give them cover to be even more restrictive.
Technology is also changing the game. Open banking, which allows third-party providers to access your bank account data with your consent, could offer a new way to fund casino accounts without using a credit card. Services like PayTo, which is being rolled out across Australian banks, enable direct bank-to-merchant transfers with real-time processing. This could bypass the credit card gambling block entirely, offering a faster and cheaper alternative to Mastercard. But adoption is still in its early stages, and casinos have been slow to integrate PayTo. It’s a promising development, but it’s not a near-term solution.
Cryptocurrency continues to gain traction as a gambling payment method. Bitcoin, Ethereum, and stablecoins like USDT offer fast, low-cost transactions with a degree of anonymity that traditional payment methods can’t match. Some casinos have gone crypto-only, abandoning fiat currencies entirely. But cryptocurrency’s volatility and the complexity of wallet management remain barriers for the average player. Mastercard’s own foray into cryptocurrency—allowing cardholders to spend crypto through their cards—could bridge this gap, but it’s still a niche feature. For now, Mastercard remains the most practical option for most Australian players, despite its limitations.
The long-term trend is toward more regulation, more restrictions, and more complexity. The days of easy, frictionless gambling deposits are numbered. Players who adapt—by understanding the fees, setting limits, and choosing casinos carefully—will navigate this changing landscape better than those who don’t. The casinos will adapt too, finding new ways to attract players in a more restrictive environment. But the fundamental dynamic won’t change: the house always has an edge, and the player always takes the risk. Mastercard is just a tool. How you use it determines whether it’s a convenience or a liability.
Understanding the Fine Print: Wagering Requirements and Bonus Traps
Every bonus at an online casino comes with terms and conditions. These documents are long, dense, and written in legal language designed to protect the casino, not the player. The most important terms are the wagering requirements, game contribution percentages, maximum bet limits, and time restrictions. A casino might offer a 100% match bonus up to $500 with a 35x wagering requirement. That sounds reasonable until you realize the requirement applies to both your deposit and the bonus. A $100 deposit gives you $200 to play with, but you need to wager $7,000 (35 x $200) before you can withdraw. The house edge on pokies is 4%, so over $7,000 in bets, you’re expected to lose $280. That’s more than the original bonus.
Game contribution percentages are another trap. Not all games contribute equally to wagering requirements. Pokies typically contribute 100%, but table games like blackjack and roulette might contribute only 10-20%. If you prefer table games, meeting the wagering requirement takes much longer. A 35x requirement on a $200 bonus means $7,000 in pokies bets, but $35,000-$70,000 in blackjack bets. The casino knows most players will gravitate toward pokies because they contribute fully, and pokies have a higher house edge than optimal blackjack strategy. The game contribution percentages are designed to steer you toward the games that make the casino the most money.
Maximum bet limits are another constraint. Most casinos limit the amount you can bet per spin or hand while a bonus is active. A typical limit is $5-$10 per bet. Exceed this limit, and the casino can void your bonus and any winnings derived from it. This rule exists to prevent players from making large bets to quickly meet wagering requirements. But it also means you can’t use aggressive betting strategies to try to clear the bonus faster. The casino controls the pace of your play, even when you’re using their “generous” bonus.
Time restrictions add pressure. Most bonuses expire after 30 days. If you don’t meet the wagering requirement within that period, the bonus and any winnings from it are forfeited. This creates a sense of urgency that encourages you to play more frequently and for longer sessions than you might otherwise. The casino benefits from this increased activity, even if you eventually lose the bonus. The time limit is a psychological tool, not a practical one. It’s designed to keep you engaged, not to give you a fair chance to clear the bonus.
Final Thoughts on Mastercard Casinos in Australia
Using Mastercard at online casinos in Australia is a practical choice, not an ideal one. It’s widely accepted, relatively secure, and familiar to most players. But it comes with fees, delays, and restrictions that other payment methods don’t have. The banks are cautious, the regulators are tightening, and the casinos are always looking for an edge. Your best defense is knowledge—understand the fees, know the terms, set your limits, and don’t believe the marketing.
The casinos that accept Mastercard in 2026 are the same ones that accepted it in 2025, with a few new faces and a few disappearances. The games are the same, the odds are the same, and the house edge is the same. The only thing that changes is the marketing. New bonuses, new promotions, new ways to convince you that this time will be different. It won’t be. The math doesn’t change. The only variable is your discipline.
So use Mastercard if it’s convenient. Set your deposit limits before you start. Read the terms of every bonus. And remember that the casino is a business, not a charity. They’re not giving you “free” money. They’re giving you an opportunity to lose yours. The only winning move is to know when to stop. And if you can’t stop, there are resources available—Gambling Help Online (1800 858 858) and Lifeline (13 11 14) are staffed by people who understand the problem. They’re not going to judge you. They’re just going to help you find a way out.
The real issue with Mastercard casinos isn’t the payment method. It’s the mindset. Players who treat gambling as entertainment, set strict budgets, and walk away when the fun stops will have a fine experience. Players who chase losses, borrow to play, and believe in systems will have a terrible one. Mastercard is just a piece of plastic. What you do with it is up to you. And if you do decide to play, at least pick a casino that doesn’t charge a fee for withdrawals. That’s the bare minimum.
Best Live Dealer Casino Online Australia 2026: The Only Guide You Need Before Losing Your Rent
独自に開発した
タイピングソフトを販売しております。
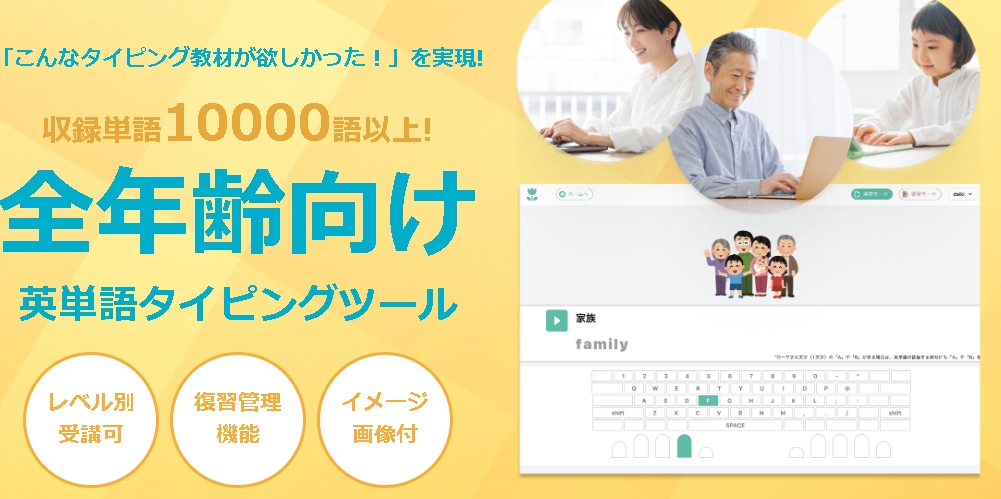
単語学習、聞き取り学習、タイピング練習はもちろん。
できなかった部分だけを重点的に学習できるように復習機能もついています。
また、中1レベルからTOEIC900点クラスまで網羅している為
無料お試し版がご利用いただけますので